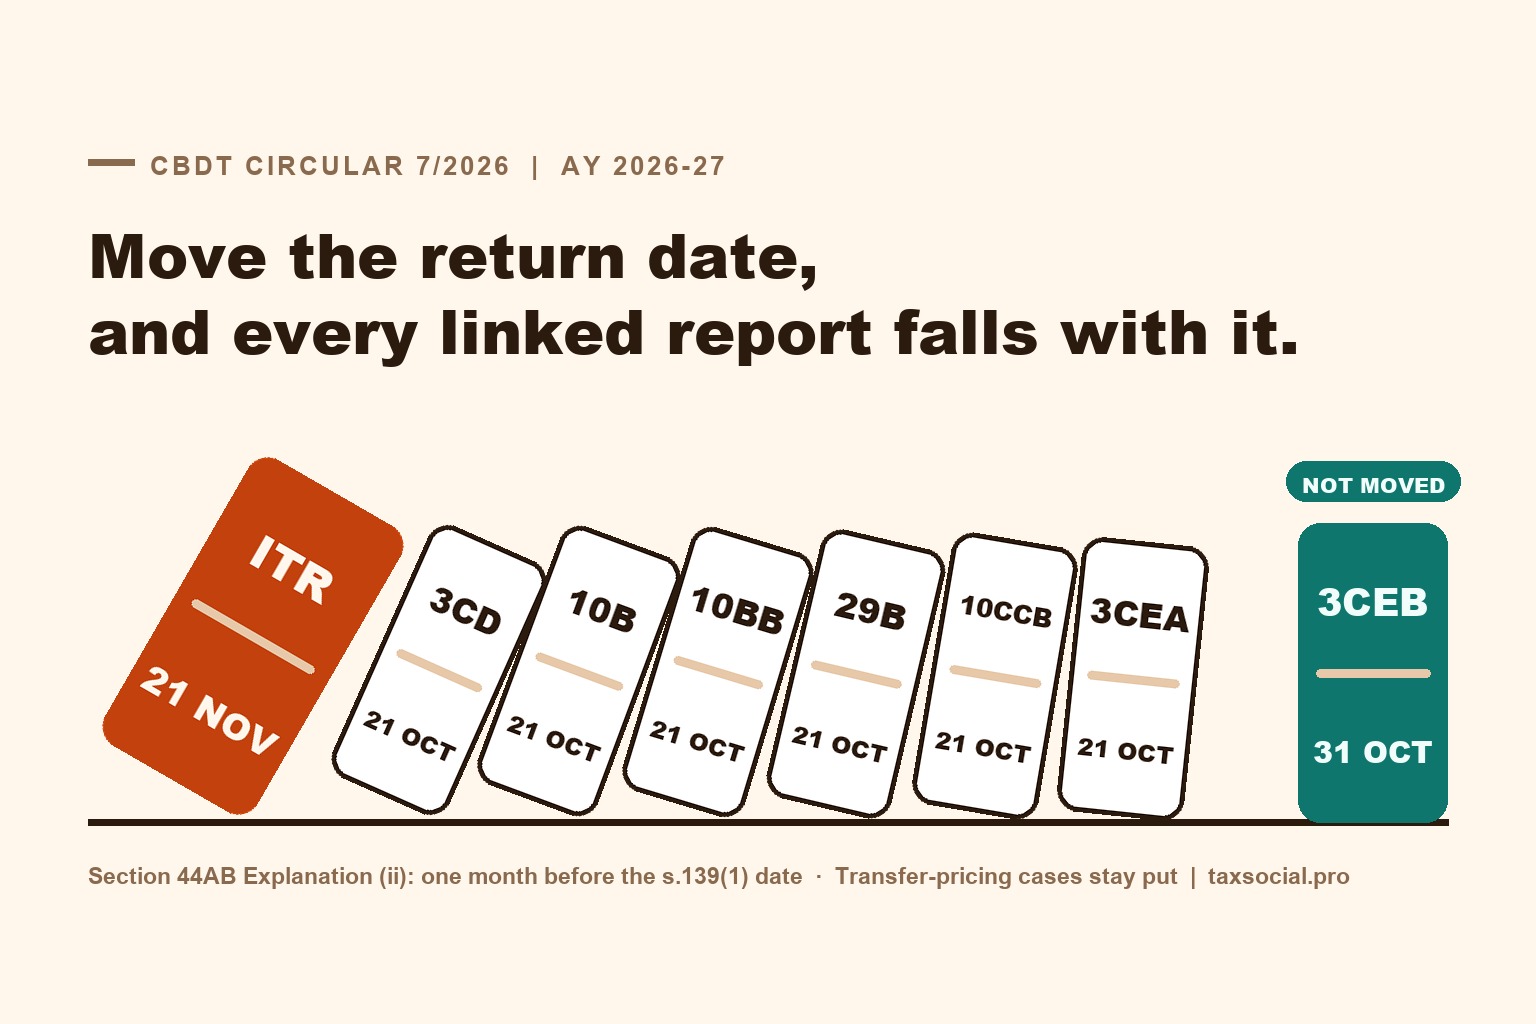
Short answer: yes, it covers them all, with one real exception. CBDT Circular No. 7/2026 of 28 September 2026 does not extend any form. It moves the return date for companies and other audited assessees from 31 October to 21 November 2026. Section 44AB defines the audit “specified date” as one month before that return date, so it becomes 21 October 2026. Every report whose section says “before the specified date referred to in section 44AB” moves with it. That includes Forms 3CA/3CB-3CD, 10B/10BB, 29B, 29C, 10CCB, 10DA, 56F and 3CEA, and the less common 3AC, 3AD, 3AE, 3CE and 66. The exception is transfer-pricing cases. They sit in a different row of the due-date table, their return date stays 30 November, and every audit report they file, not just Form 3CEB, stays due on 31 October.
1. What the circular actually says
The operative text is two sentences. First, the Board, under Section 119 of the Income-tax Act, 1961 read with Section 536 of the Income-tax Act, 2025, extends the due date for the AY 2026-27 return “for the persons referred in sl.no.2 of the table below Explanation 2 to sub-section (1) of section 139” from 31.10.2026 to 21.11.2026. Second: “Consequently, the specified date for furnishing of report of audit” for AY 2026-27 “shall stand extended to 21.10.2026 in terms of clause (ii) of Explanation to section 44AB”.
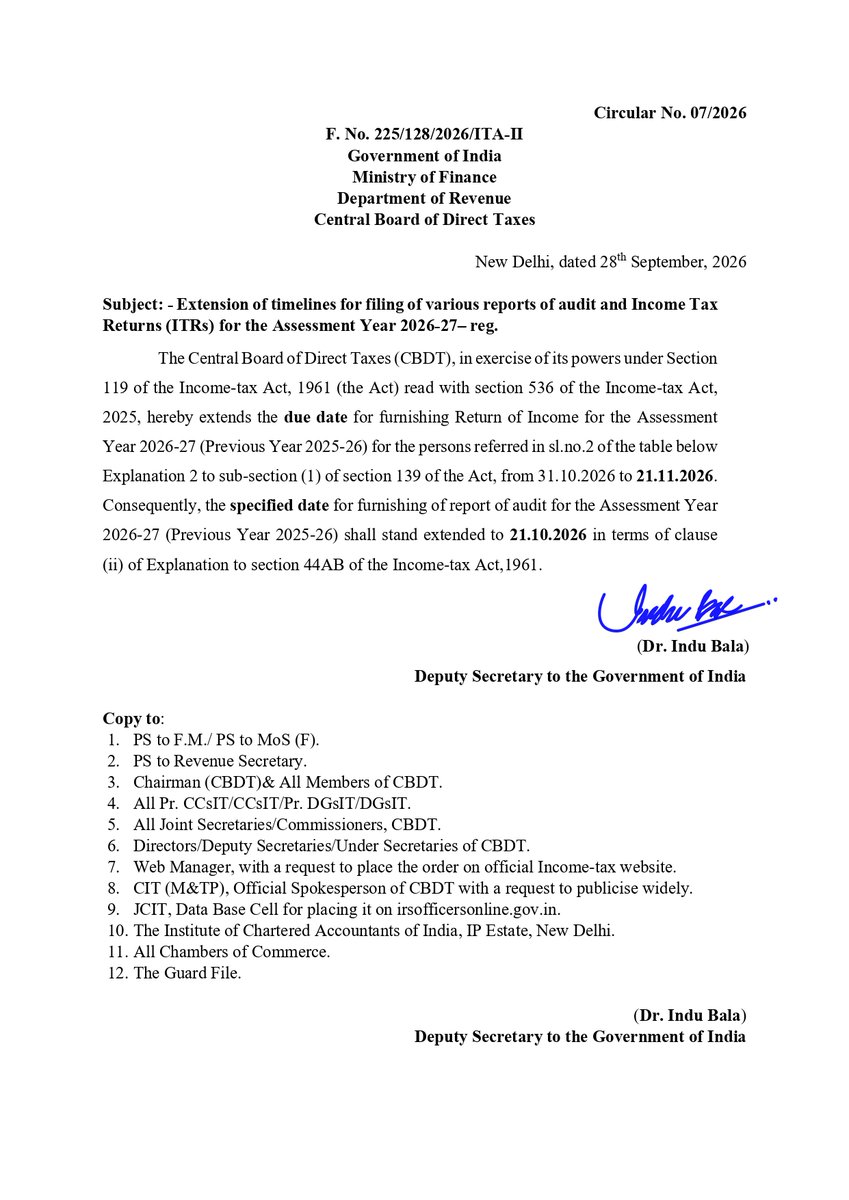
The order matters. The Board moved the return date and let the statute move the audit date. That is why it matters that the circular names no forms. It did not need to.
Why both Acts are cited: AY 2026-27 is income of FY 2025-26, which is still assessed under the 1961 Act, even though the 2025 Act has been in force since 1 April 2026. Section 536 of the 2025 Act is the repeal-and-savings provision that keeps the old Act, and the Board’s power under its Section 119, working for that year. The section numbers in this article are therefore 1961-Act numbers, and correctly so. Which Act applies to which year is set out separately.
2. Who is in “Sl. No. 2”
The Finance Act, 2026 rewrote Explanation 2 to Section 139(1) as a four-row table, with effect from 1 March 2026. The circular moves one row of it.
| Sl. No. | Who | Condition | Return date, AY 2026-27 |
|---|---|---|---|
| 1 | Any assessee, including partners of the firm and a Section 5A spouse | Section 92E applies (a transfer-pricing report is required) | 30 November 2026. Not extended. |
| 2 | (i) Every company; (ii) any other assessee whose accounts must be audited under the Income-tax Act or any other law; (iii) a partner of such a firm, and a Section 5A spouse | Section 92E does not apply | 21 November 2026 (was 31 October) |
| 3 | Business or professional income, accounts not required to be audited; partners of such firms | Section 92E does not apply | 31 August 2026. Not extended (already passed). |
| 4 | Everyone else | — | 31 July 2026. Not extended (already passed). |
Three things follow from the wording of row 2 that are easy to miss:
- Every company is in it unless Section 92E applies, whatever its turnover and whether or not it needs a Section 44AB audit.
- “Or any other law” brings in an LLP audited under the LLP Act, or a co-operative society audited under its State Act, even where no Section 44AB audit is needed. Their return date moves to 21 November too.
- Partners of an audited firm are in row 2 in their own right. A partner’s personal return is due 21 November, although the partner files no audit report.
3. The reports that move to 21 October 2026
This is the question everyone is asking. Almost every report tied to the tax-audit date is written the same way in its own section: the report must be furnished “before the specified date referred to in section 44AB”. Those sections do not carry a date of their own. They borrow Section 44AB’s. Section 44AB’s date is one month before the Section 139(1) date. Move that, and everything downstream moves. For a Sl. No. 2 assessee:
| Report | Form | Where the date comes from | New date |
|---|---|---|---|
| Tax audit | 3CA or 3CB, with 3CD | s.44AB, Explanation (ii) | 21 October 2026 |
| Audit of a trust or institution claiming ss.11 and 12 | 10B or 10BB | s.12A(1)(b)(ii): “before the specified date referred to in section 44AB” | 21 October 2026 |
| Audit of a fund or institution under s.10(23C) | 10B or 10BB | The audit proviso to s.10(23C), same words | 21 October 2026 |
| MAT book-profit certificate | 29B | s.115JB(4), same words | 21 October 2026 |
| AMT certificate | 29C | s.115JC(3), same words | 21 October 2026 |
| Undertaking deductions under ss.80-IA, 80-IAB, 80-IAC, 80-IB, 80-IC, 80-IE | 10CCB and the related forms | s.80-IA(7), which s.80-IAB(3), s.80-IAC(4), s.80-IB(13), s.80-IC(7) and s.80-IE(6) apply | 21 October 2026 |
| Deduction for additional employee cost | 10DA | s.80JJAA(2)(c), same words | 21 October 2026 |
| SEZ unit deduction | 56F | s.10A(5), which s.10AA(8) applies | 21 October 2026 |
| Slump sale net-worth report | 3CEA | s.50B(3), same words | 21 October 2026 |
| Tea, coffee or rubber development account | 3AC | s.33AB(2), same words | 21 October 2026 |
| Site restoration fund | 3AD | s.33ABA(2), same words | 21 October 2026 |
| Amortisation of preliminary expenses, or of prospecting expenditure (first year of the claim) | 3AE | s.35D(4) and s.35E(6), same words | 21 October 2026 |
| Audit of a non-resident’s royalty or fees for technical services under s.44DA | 3CE | s.44DA(2), same words | 21 October 2026 |
| Tonnage tax company | 66 | s.115VW, same words | 21 October 2026 |
Every entry in that table was read against the current text of the section on the department’s site, not from memory. The table covers the reports we could tie to a section; treat it as the main list, not as an exhaustive one. The test for anything not in it is the same: if its section says “before the specified date referred to in section 44AB”, it moves.
If the Rule and the section disagree, the section decides. Some of the Rules that prescribe these forms still say the report goes “along with the return of income”. Rule 19AB, for Form 10DA, does. The sections were later amended to the specified-date wording, and the Rules were not. A rule cannot override the section it serves, so the date is the specified date: 21 October for a row 2 assessee.
A word on trusts. A trust whose accounts must be audited under Section 12A is an assessee “whose accounts are required to be audited under this Act”, so it sits in row 2. Its Form 10B or 10BB is due 21 October and its ITR-7 on 21 November. Section 12A(1)(ba) requires the return within the time allowed under Section 139(1) or (4), and the extended date is the 139(1) date.
4. What is not covered
Transfer-pricing cases, entirely. If Section 92E applies to you (an international transaction or a specified domestic transaction in FY 2025-26), you are in row 1, not row 2, and the circular does not touch row 1. Your return stays due on 30 November 2026. Your “specified date” under Section 44AB stays one month before that, at 31 October 2026. So does your Form 3CEB, because Section 92F(iv) defines its specified date the same way. So does every other report in the section 3 table that applies to you: Form 3CA/3CB-3CD if you are liable to a Section 44AB audit, Form 29B if you are a MAT company, and so on. Some quick summaries say only “3CEB is not extended”. That understates it: the transfer-pricing assessee’s whole audit calendar is unchanged. It ends up ten days behind the rest, which is where it would have been anyway.
Watch the boundary. One international transaction with an associated enterprise puts a company in row 1. A company that assumes “companies got 21 November” without checking for a Section 92E report can miss a 31 October date.
Non-audit returns. Rows 3 and 4 (31 August and 31 July) are not extended. Those dates have passed, and nothing in this circular reopens them.
Anything under another law. The circular is a Section 119 order under the Income-tax Act. It does not move the Companies Act AGM deadline or any MCA or GST date. The AGM position for 30 September 2026 is here.
Reports whose deadline is written differently. The rule in section 3 only works for a report whose section borrows the Section 44AB date or the Section 139(1) date. A form with a fixed calendar date, or a date tied to something else, follows its own words. Check the section before assuming.
5. Why this year’s wording is narrower than 2025, and why it does not matter
The question is fair. The 2025 circulars spelled the reach out. Circular 14/2025 extended the specified date for “report of audit under any provisions of the Act”, and Circular 15/2025 said “report of audit under the provisions of the Act”. That is why professional bodies could confirm at the time that Forms 10B and 10BB were covered. Circular 7/2026 says only “report of audit”, and cites Section 44AB.
The difference comes from how the circulars work, not from any change of policy. Circular 14/2025 moved the specified date directly, and left the return date where it was. A direct extension of a date is only as wide as its words, so it had to say which reports it meant. That is also what went wrong in 2025: the Gujarat High Court held in October 2025 that the Board ought to have moved the return date as a consequence, and directed it to. Circular 15/2025 then did it the other way round. Circular 7/2026 follows the 15/2025 pattern from the start: move the return date, and the specified date follows “consequently”. Once the return date moves, it does not matter how few forms the circular names. Section 12A, Section 115JB, Section 80-IA and the rest do not look at the circular. They look at Section 44AB, and Section 44AB looks at Section 139(1).
The press release issued the same day says “report of audit under the provisions of the Income-tax Act, 1961”, which is the 2025 wording. If you want something to put on file for a trust client, the press release is the plain statement. The circular is the legal instrument.
6. What else moves with the return date
Because the circular extends the Section 139(1) date itself for row 2, anything that turns on that date moves too:
- Chapter VI-A Part C deductions. Section 80AC denies deductions such as those under Sections 80-IA, 80-IB, 80-IC and 80JJAA unless the return is filed “on or before the due date specified under sub-section (1) of section 139”. For row 2 that is now 21 November.
- Opting out of the new regime. An individual or HUF with business income exercises the Section 115BAC(6)(i) option in Form 10-IEA on or before the Section 139(1) date. For an audited proprietor, or a partner in an audited firm, that is now 21 November.
- Carrying losses forward. A business loss is carried forward only on a return filed within the time allowed under Section 139(1). For row 2, 21 November is within time.
- The trust’s own return under Section 12A(1)(ba), as above.
7. Section 234A: the one thing the circular does not say
Circular 7/2026 is silent on interest under Section 234A, as Circular 15/2025 was last year. Explanation 1 to Section 234A defines “due date” as “the date specified in sub-section (1) of section 139 as applicable in the case of the assessee”. The circular extends that date for row 2, so on the words, interest for late filing should run from 22 November, not 1 November. But the circular does not say so expressly, and 234A interest is small against the risk of an argument. If you know the self-assessment tax, pay it by 31 October and file the return when it is ready. Section 234B interest on a shortfall in advance tax runs regardless, and the extension does not change that.
8. The penalty date moves too, and upload still means upload
Section 271B turns on failure to furnish the report “by the specified date”. For a row 2 assessee that date is now 21 October 2026. A report signed on 20 October and uploaded on 22 October is late. For the size of the exposure (one-half per cent of turnover, capped at Rs 1,50,000, with a reasonable-cause defence under Section 273B), see the Section 271B piece. Its figures apply unchanged; only the date is different.
9. The practical list
- Sort your clients by row, not by form. Row 2 gets 21 October / 21 November. Row 1, meaning anyone with a Section 92E report, stays at 31 October / 30 November.
- Trusts: Form 10B or 10BB by 21 October, ITR-7 by 21 November.
- MAT companies: Form 29B by 21 October, and Form 3CD by the same date where a Section 44AB audit also applies. A MAT company with a transfer-pricing report files them by 31 October.
- Chapter VI-A deduction claimants (80-IA, 80-IB, 80-IC, 80JJAA and the like): the report by 21 October and the return by 21 November, or the deduction is at risk under Section 80AC.
- SEZ units under Section 10AA: Form 56F by 21 October. Section 80AC does not govern Section 10AA; the report condition comes from Section 10A(5), which Section 10AA(8) applies.
- Self-assessment tax by 31 October where you can.
- Use the extra three weeks on the review, not the queue. The Form 3CD errors ICAI’s review board keeps finding is the list to work down.
FAQ
Has the tax audit due date for AY 2026-27 been extended? Yes. By Circular 7/2026 of 28 September 2026, the specified date is 21 October 2026 for companies and audited assessees other than transfer-pricing cases, and their return date is 21 November 2026.
Are Forms 10B and 10BB extended to 21 October? Yes, for a trust or institution whose accounts must be audited. Section 12A(1)(b)(ii) and the Section 10(23C) proviso tie the report to the specified date under Section 44AB.
Is Form 29B (MAT) extended? Yes. Section 115JB(4) uses the Section 44AB specified date. So does Section 115JC(3) for Form 29C.
Is Form 10CCB extended? Yes. Section 80-IA(7) uses the Section 44AB specified date, and Sections 80-IB(13) and 80-IC(7) apply it.
Is Form 3CEB extended? No. Section 92E cases are in row 1 of the table, which the circular does not touch. Their return is still due 30 November 2026 and their audit reports, 3CEB included, 31 October 2026.
I have one international transaction. Which date is mine? 31 October for the reports, 30 November for the return.
Does the partner of an audited firm get 21 November? Yes. Partners of firms whose accounts must be audited are in row 2.
Is 234A interest waived until 21 November? The circular does not say. On the words of Section 234A, the extended date should apply, but pay self-assessment tax by 31 October to take the question off the table.
Does this move the AGM date? No. That is a Companies Act date, and this is an Income-tax Act circular.
The day-by-day record of how the extension came about, with the representations and the earlier circulars, is on the AY 2026-27 extension tracker.
Sources
- CBDT Circular No. 07/2026, F. No. 225/128/2026/ITA-II, dated 28 September 2026; CBDT press release of the same date.
- CBDT Circular No. 14/2025 dated 25 September 2025 and Circular No. 15/2025, F. No. 225/131/2025/ITA-II, dated 29 October 2025.
- Finance Act, 2026, s.5 (Explanation 2 to s.139(1) substituted w.e.f. 1 March 2026).
- Income-tax Act, 1961: ss.10(23C), 10A(5), 10AA(8), 12A(1)(b) and (ba), 33AB(2), 33ABA(2), 35D(4), 35E(6), 44AB Explanation (ii), 44DA(2), 50B(3), 80AC, 80-IA(7), 80-IAB(3), 80-IAC(4), 80-IB(13), 80-IC(7), 80-IE(6), 80JJAA(2)(c), 92E, 92F(iv), 115BAC(6), 115JB(4), 115JC(3), 115VW, 119, 234A, 271B, 273B; current text as published on incometaxindia.gov.in. Income-tax Rules, 1962, Rule 19AB.
- Income-tax Act, 2025, s.536.
Comments (0)
No comments yet. Be the first to comment!