#Income Tax

82 articles

Income tax is where Indian tax practice changes most often — through annual Finance Acts, fresh CBDT notifications, year-end circulars, and judicial interpretation. The articles tagged Income Tax on TaxSocial cover the parts that matter most for individual taxpayers and finance professionals filing returns, planning advance tax, and reading the income-tax notice traffic: ITR forms and which one applies, capital gains computation under the new Act, TDS and TCS interactions, presumptive taxation under Sections 44ADA and 44AB, the Section 87A rebate, new-regime mechanics, and the practical consequences of the Income-tax Act, 2025 commencement on 1 April 2026. Each article is written against the bare Act text and cross-checked against CBDT notifications. Treat this hub as the master index for income-tax content on the Platform.

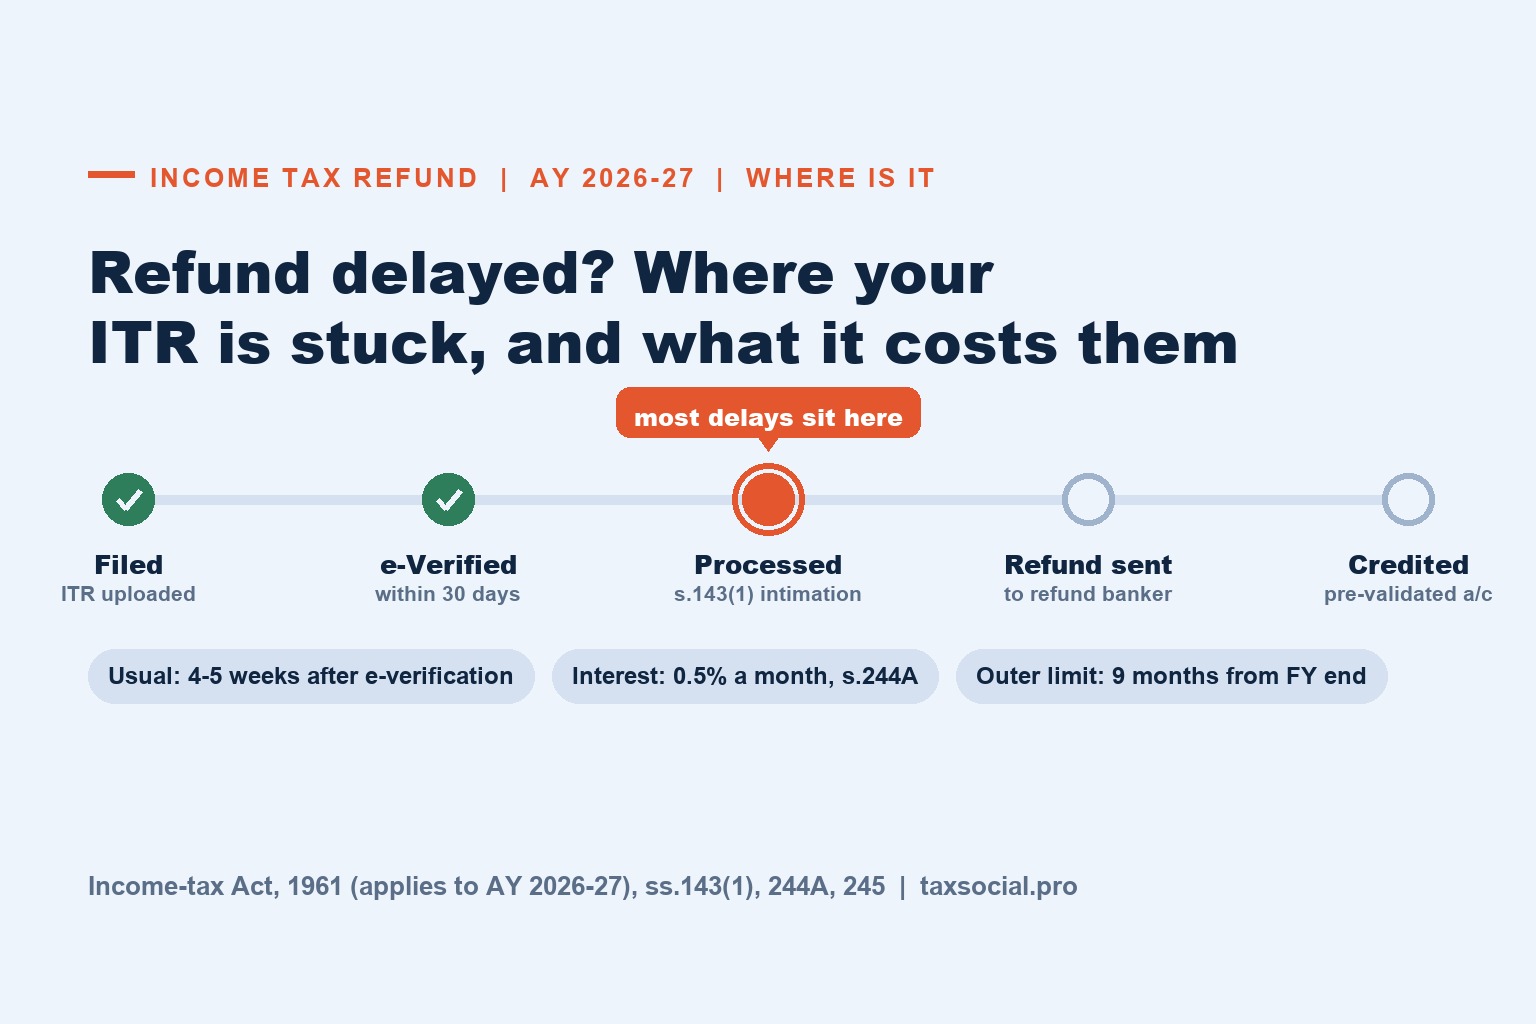
Income Tax Refund Delayed for AY 2026-27? How Many Days a Refund Takes, How to Check the Status, the Eight Reasons It Is Stuck, and the Interest You Are Owed

Najma K
Najma K · Sep 17
A refund for AY 2026-27 usually lands four to five weeks after e-verification; the legal outer limit is nine months from the end of the financial year the return was filed in. How to read the portal status, the eight reasons a refund stalls, and the 0.5% a month interest under Section 244A.

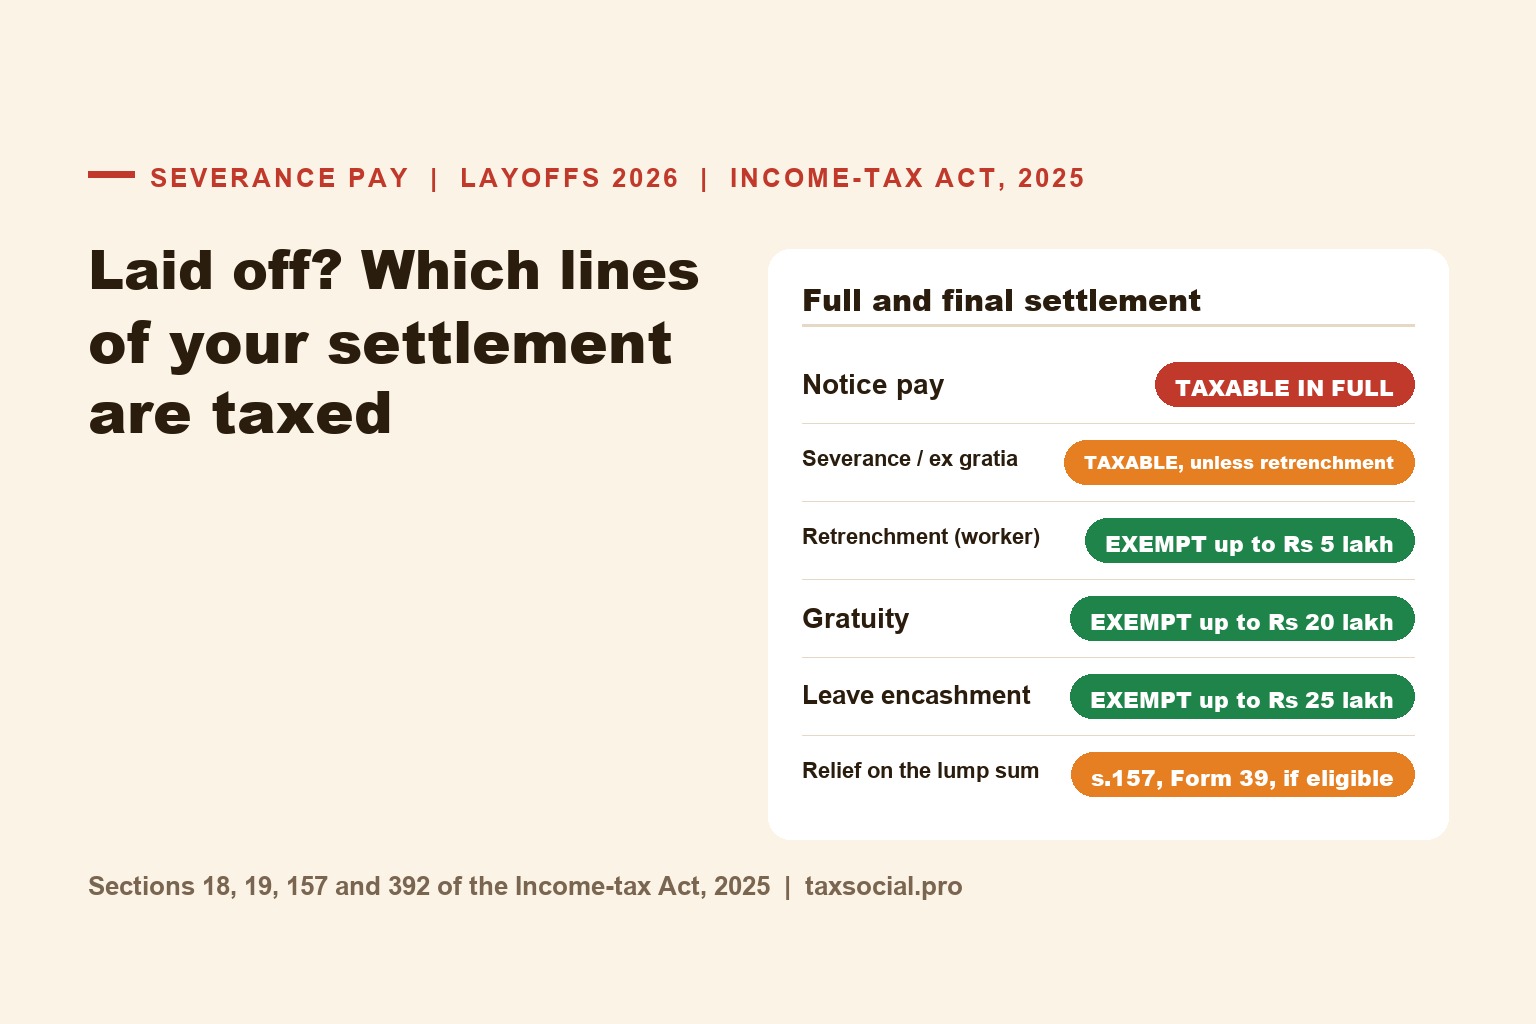
Severance Pay Tax in India (2026): Is Your Layoff Package Taxable? Notice Pay, Ex Gratia, Retrenchment Compensation, Gratuity and Leave Encashment Under the Income-tax Act, 2025

Deep Jasani
Deep Jasani · Sep 17
Laid off in 2026? Your settlement is taxed line by line under the Income-tax Act, 2025: notice pay in full; severance as profits in lieu of salary unless it is retrenchment compensation to a worker (up to Rs 5 lakh deductible); gratuity up to Rs 20 lakh; leave encashment up to Rs 25 lakh.

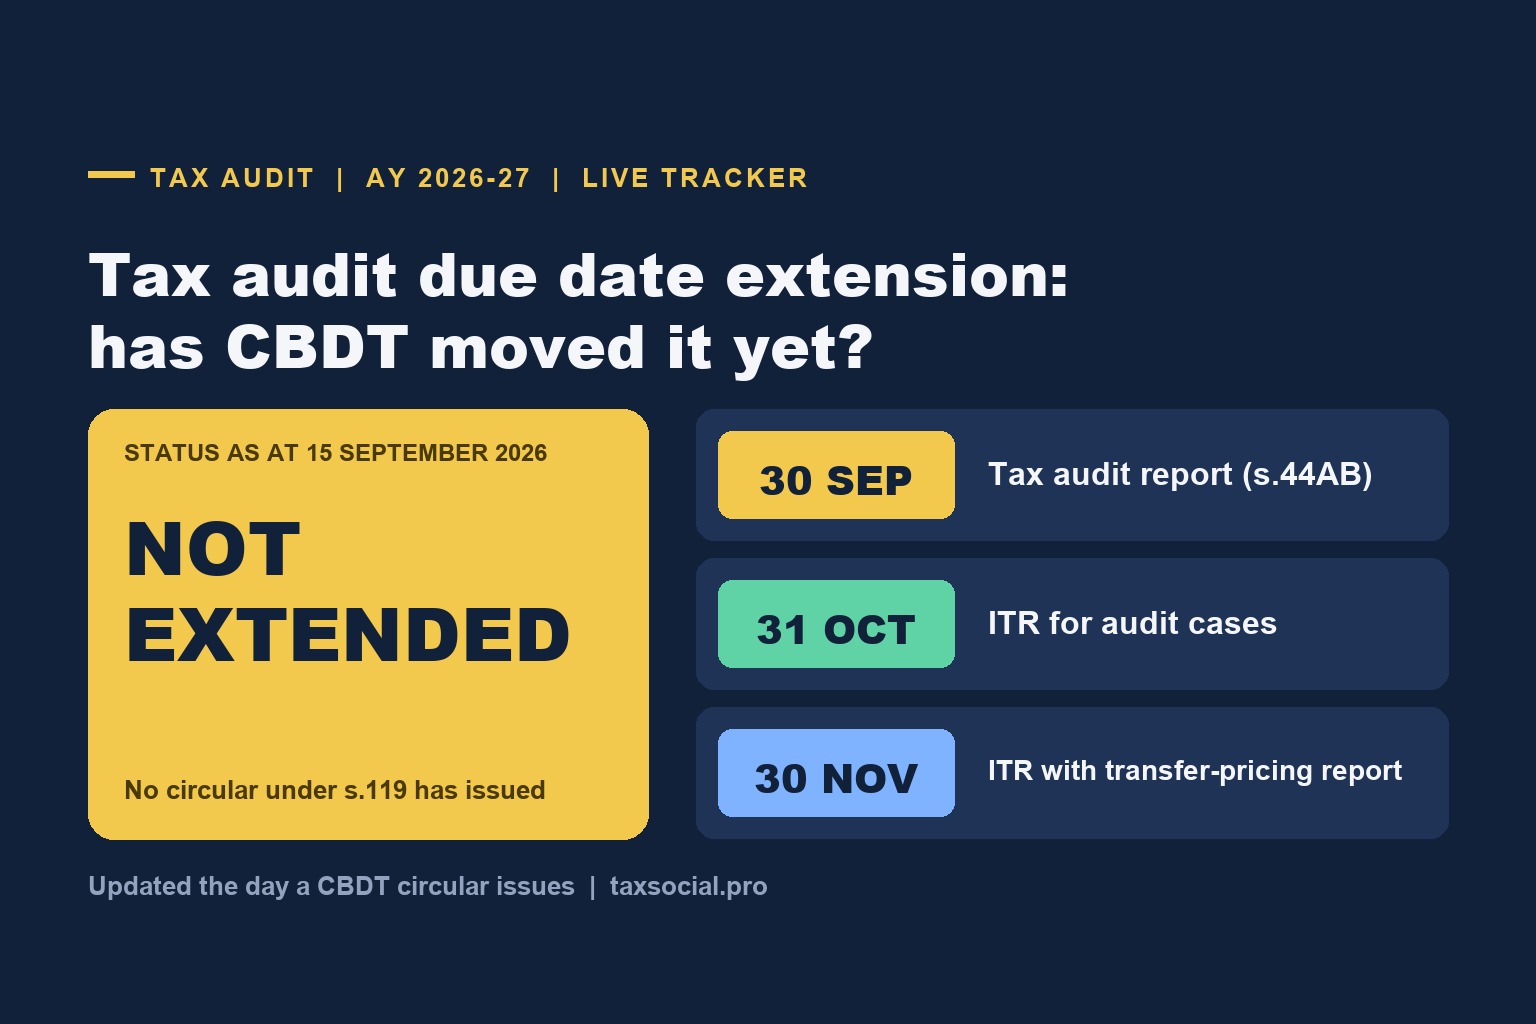
Tax Audit Due Date Extension AY 2026-27: Latest Update as at 17 September 2026 (No CBDT Circular Yet, 30 September Stands)

Harsh Vyas
Harsh Vyas CA · Sep 17
Status as at 17 September 2026: the AY 2026-27 tax audit report is still due 30 September. No CBDT circular under Section 119 has issued. Dated update log, the 2022-2025 extension record with circular numbers, who has asked for what, where a circular appears first, and what a late report costs.

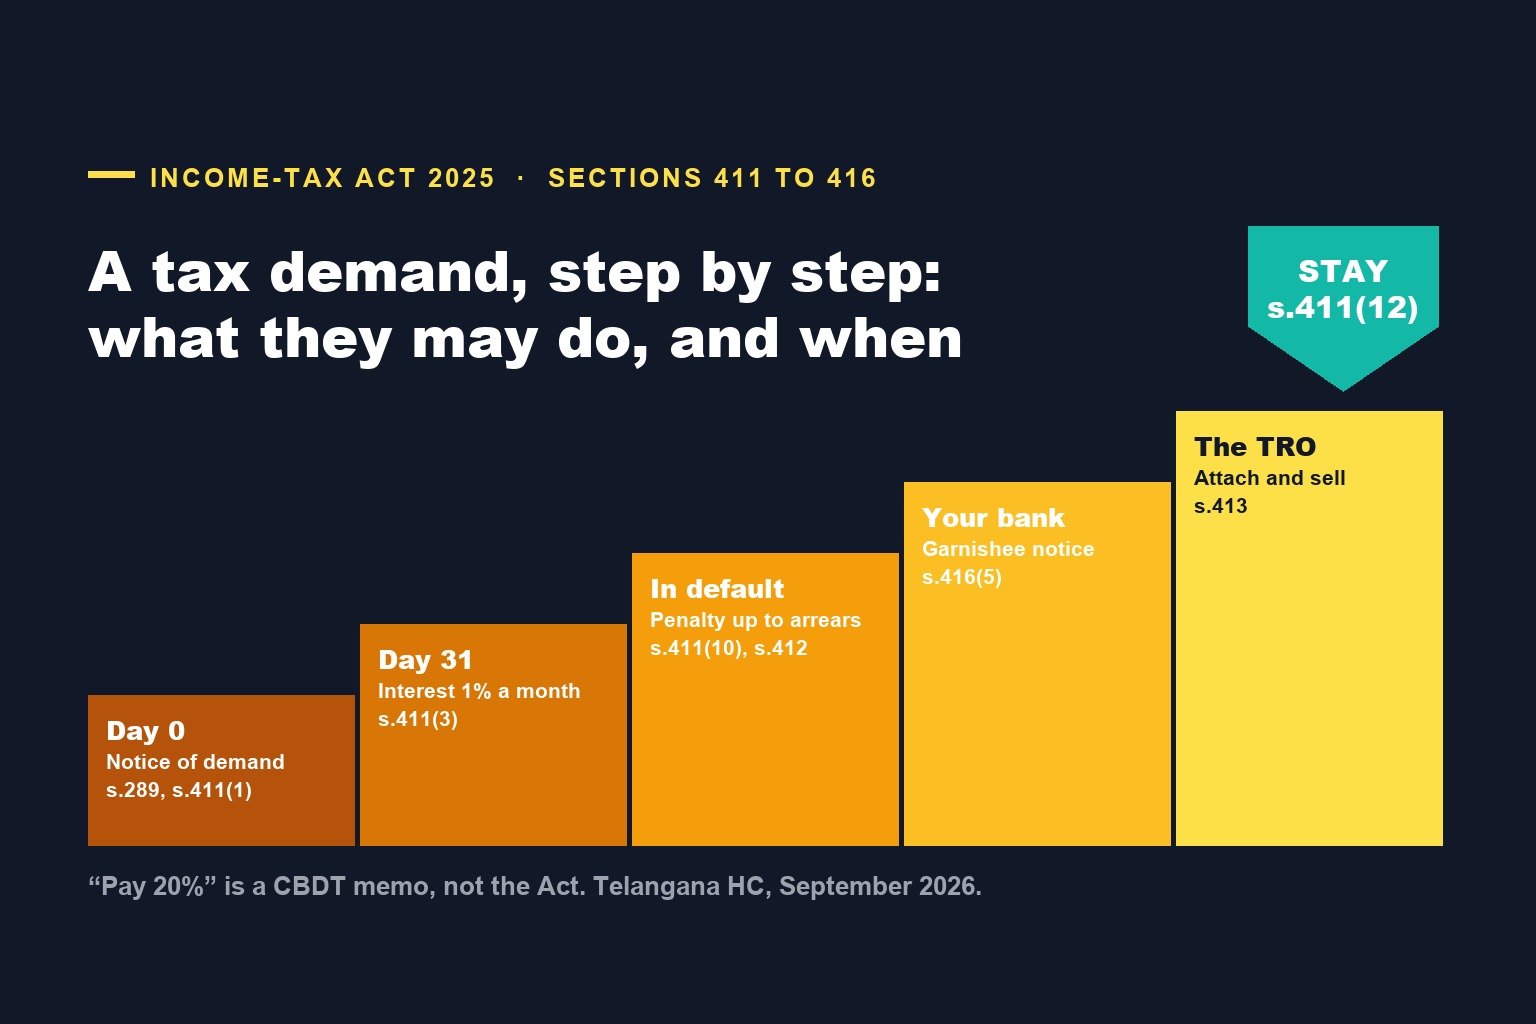
You Have a Tax Demand. Here Is What the Department Can Actually Do, and When: The 30-Day Clock, 1% a Month, the Notice to Your Bank, and Why "Pay 20% for a Stay" Is Not the Law (Telangana High Court, September 2026)

Vijay R S
Vijay R S · Sep 14
A demand notice starts a 30-day clock, then 1% a month, then "assessee in default", then a notice to your bank under section 416. Filing an appeal stops none of it; a stay under section 411(12) does. The Telangana High Court has just set aside stay orders that treated the CBDT's 20% as the rule. The statute, the memoranda, the Budget's 10%, and a checklist.

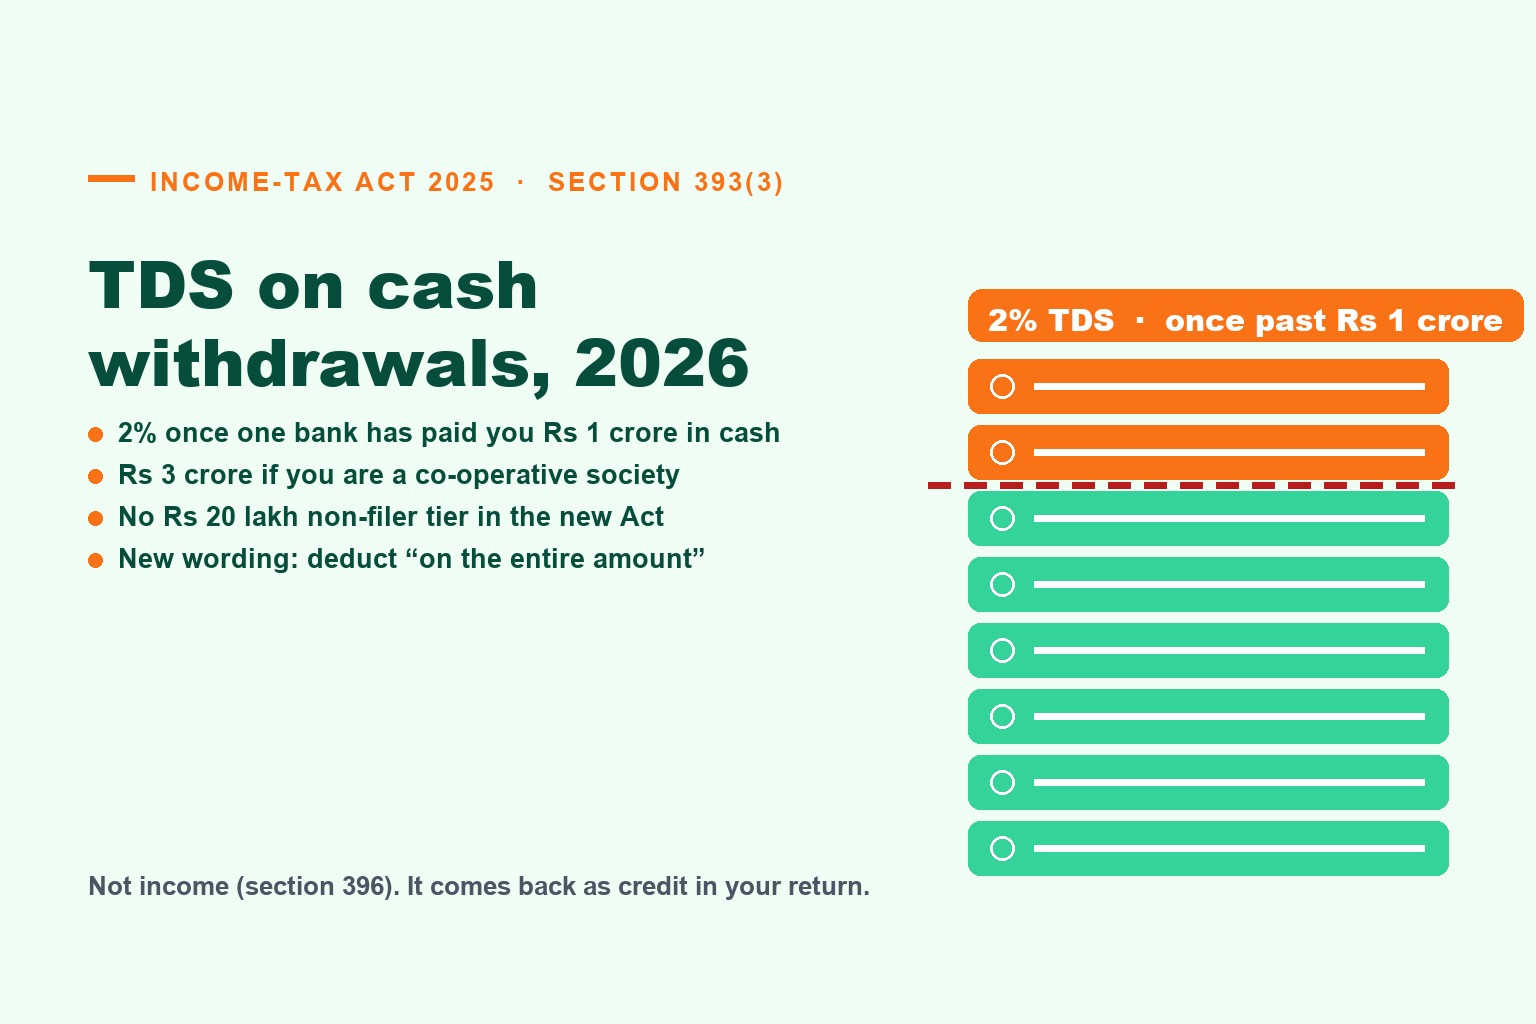
TDS on Cash Withdrawals From 1 April 2026: Section 393(3) Replaces 194N, the Rs 20 Lakh Non-Filer Tier Is Gone, and the New Text Says "Entire Amount"

Mrunmai Madaye
From 1 April 2026 the bank deducts 2% on cash withdrawals above Rs 1 crore (Rs 3 crore for a co-operative society) under section 393(3) of the Income-tax Act, 2025. Two things changed that most bank FAQs have not caught: the old non-filer tier is not in the new Act, and the new text says the deduction is "on the entire amount".

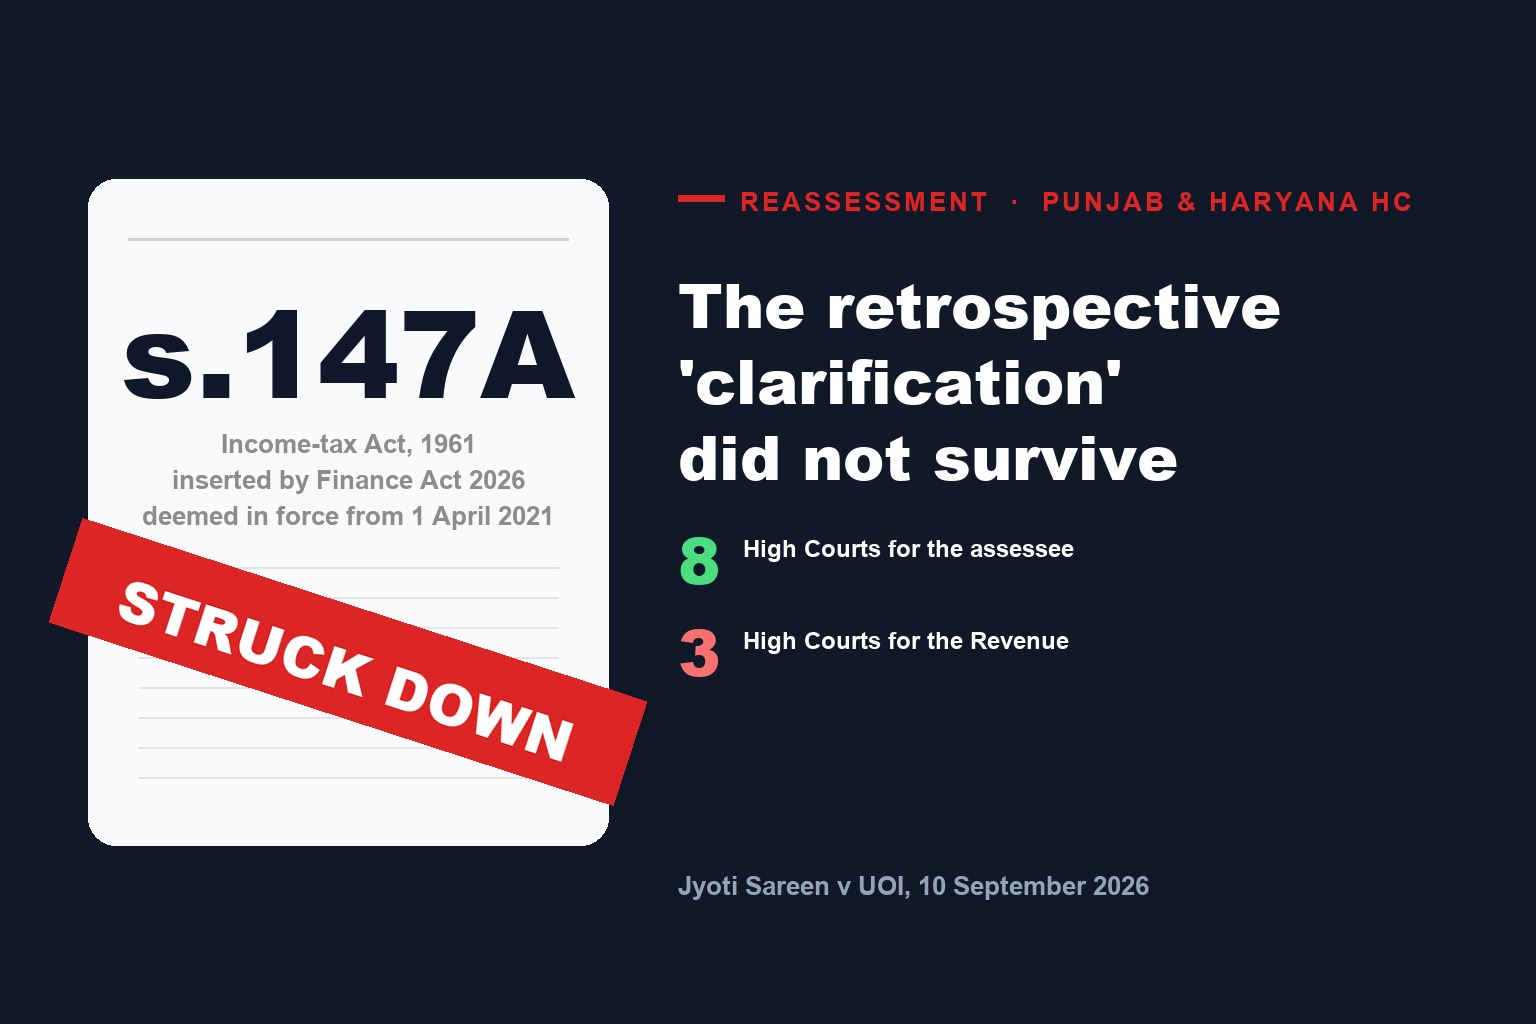
Section 147A Struck Down: Punjab & Haryana High Court Holds the Retrospective "Clarification" Unconstitutional and Quashes JAO-Issued Section 148 Notices (Jyoti Sareen, 10 September 2026)

Vijay R S
Vijay R S · Sep 13
On 10 September 2026 the Punjab & Haryana High Court struck down Section 147A of the Income-tax Act, 1961, the Finance Act 2026 insertion that retrospectively made the jurisdictional officer the "Assessing Officer" for Sections 148 and 148A, and set aside the JAO-issued notices before it. What was decided, why, who it binds, and what to do with a live notice.

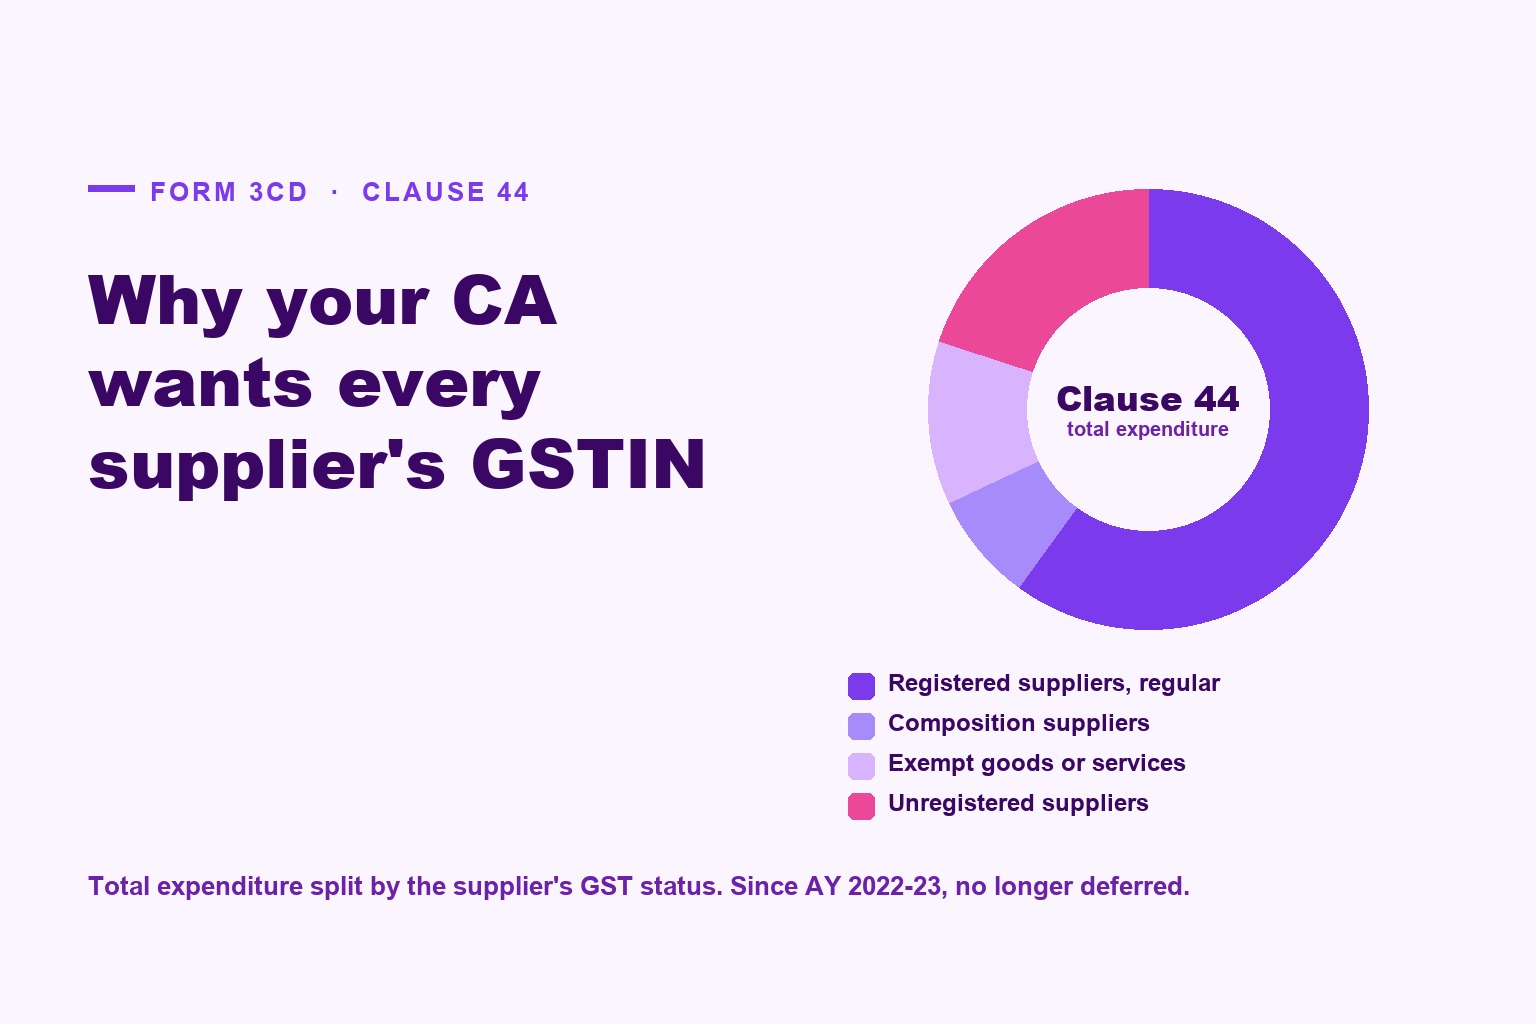
Form 3CD Clause 44 (GST Break-up of Expenditure): Why Your CA Is Asking for Every Supplier's GST Number

Sachin Mohite
Sachin Mohite · Sep 11
Clause 44 of Form 3CD makes the tax auditor split your total expenditure by the supplier's GST status: exempt goods or services, composition dealers, other registered suppliers, and unregistered suppliers. It was deferred four times and has been live since AY 2022-23. What the columns mean, what is excluded, how to build the data from GSTR-2B and the purchase register, and why the number has to tie to your GST returns.

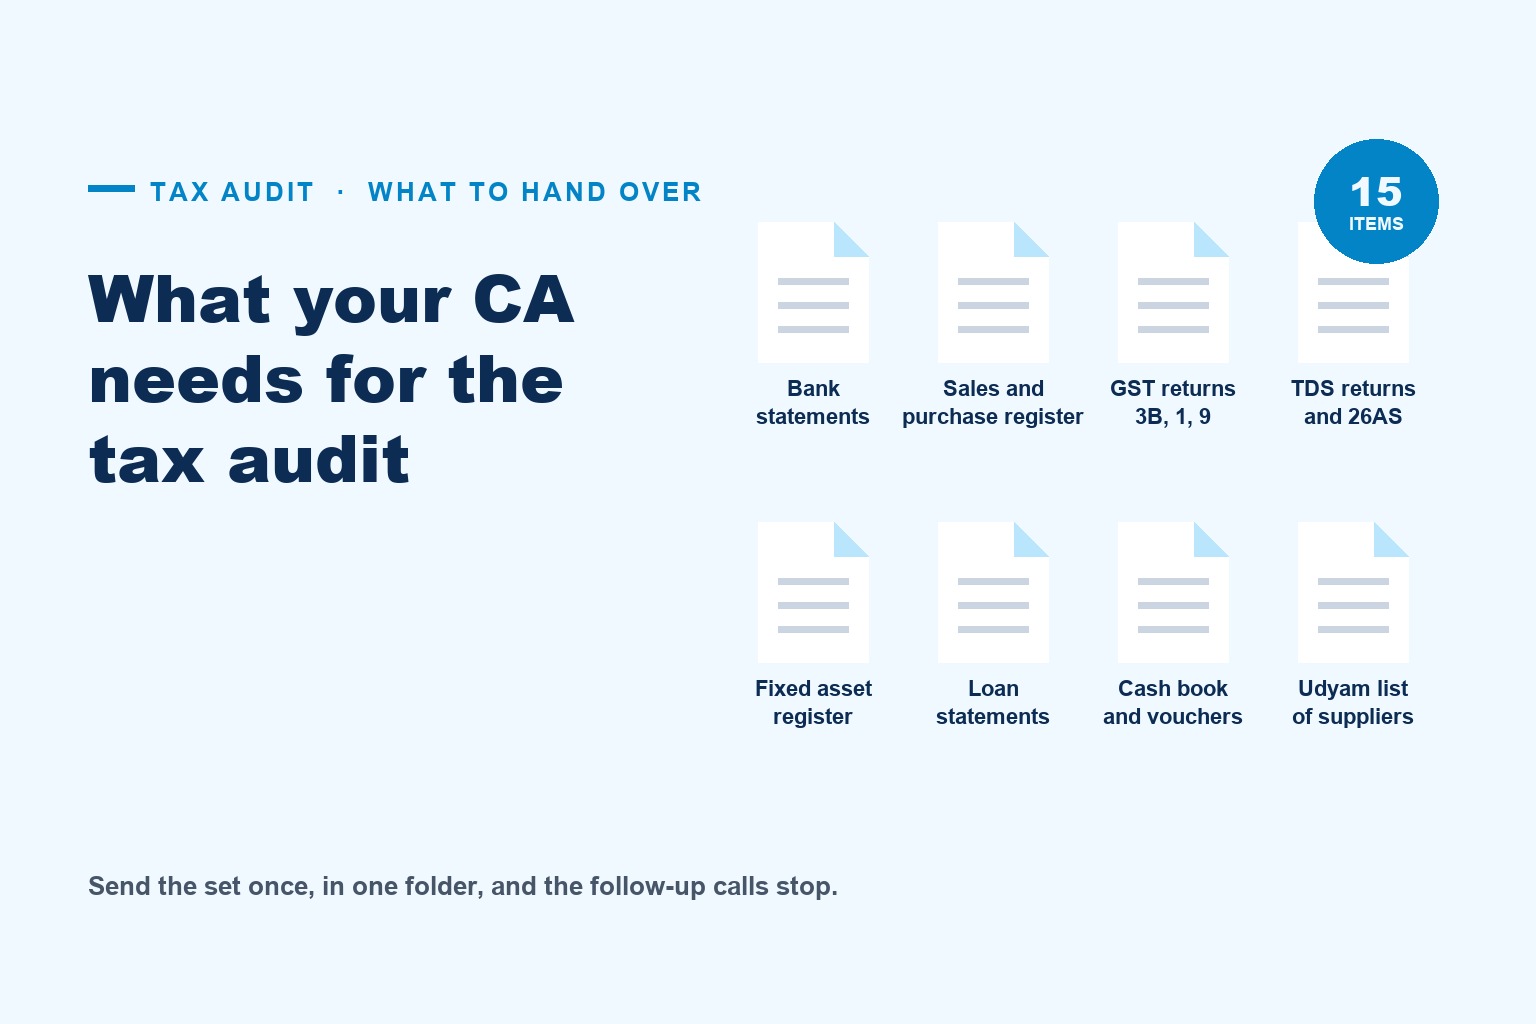
Documents Your CA Needs for the Tax Audit: The 15-Item Checklist for AY 2026-27 (and Which Form 3CD Clause Each One Feeds)

Harsh Vyas
Harsh Vyas CA · Sep 11
The tax audit report for AY 2026-27 is due 30 September 2026. Here is the list a tax auditor needs from a client, in one folder: books and bank statements, GST and TDS returns, the fixed-asset and loan registers, the cash-transaction schedule, the MSME supplier list, the supplier GSTIN master for clause 44, and eight more, each tied to the Form 3CD clause it answers.

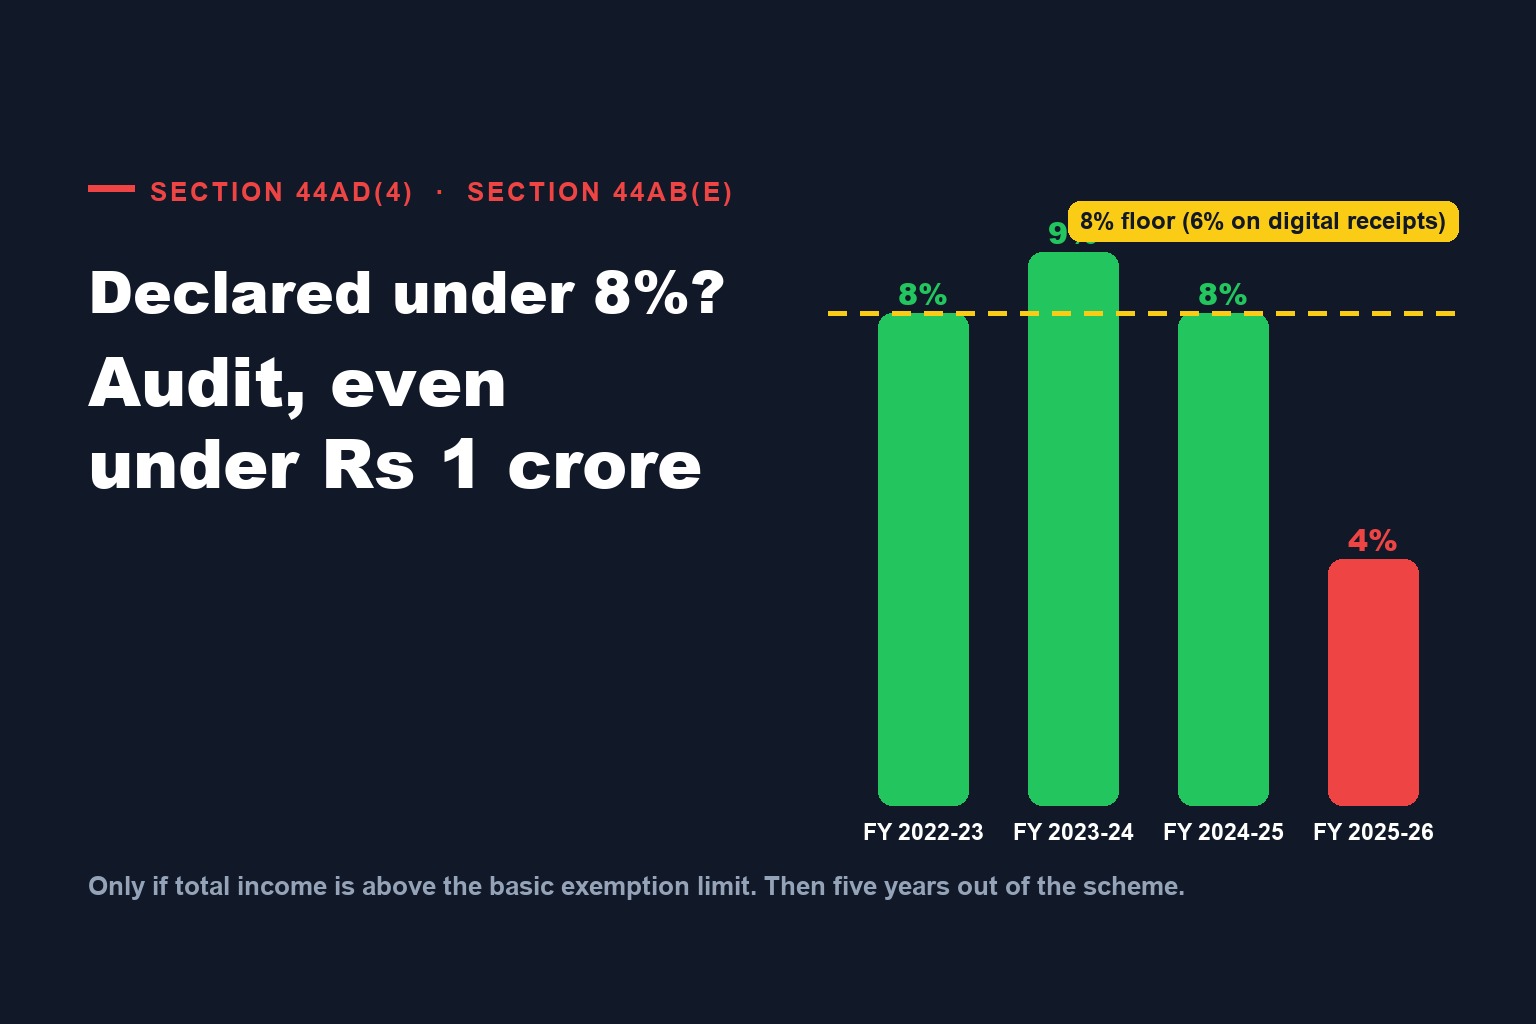
Declared Profit Below 8% or 6%? You May Need a Tax Audit Even Under Rs 1 Crore: The Section 44AD(4) Trap, and Who It Does Not Catch

Vijay R S
Vijay R S · Sep 11
Turnover under Rs 1 crore does not settle the tax-audit question. If you used Section 44AD in any of the last five years and now declare below 8% (6% on digital receipts), Section 44AD(4) applies, and Section 44AB(e) requires an audit when your total income exceeds the basic exemption limit (Rs 4 lakh, new regime). A first-time low-profit declarant who never opted in is NOT caught.

Help

Need help? Browse our Help Center for guides on using TaxSocial.

Visit Help Center

View Plans