#Section 44AB

13 articles

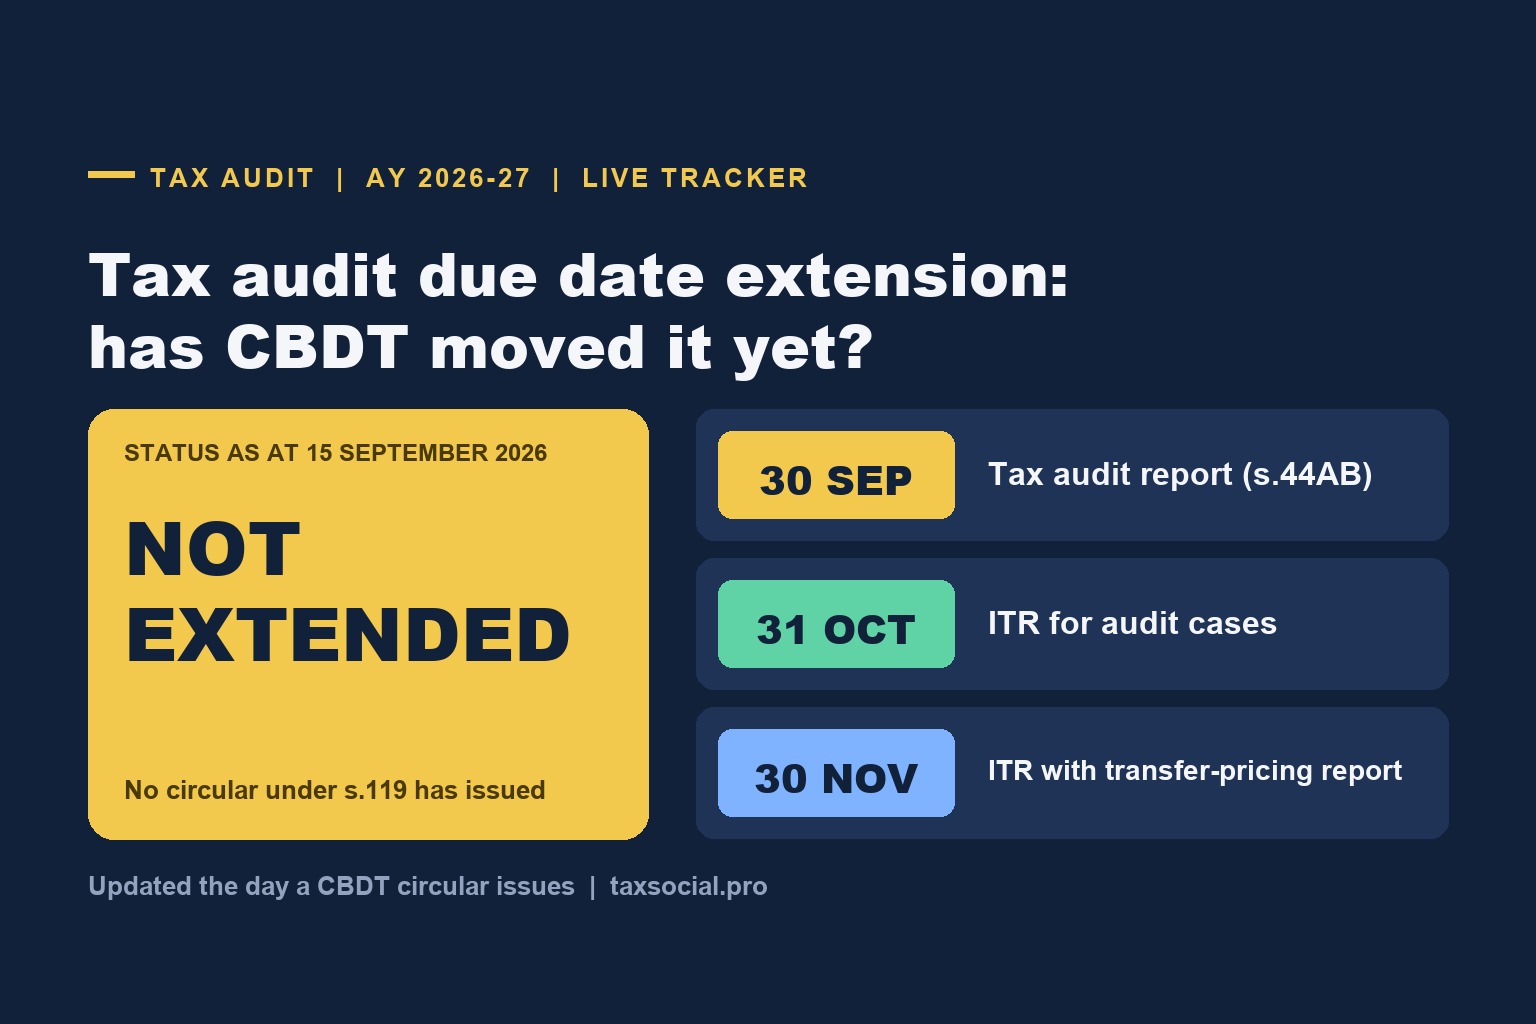
Tax Audit Due Date Extension AY 2026-27: Latest Update as at 17 September 2026 (No CBDT Circular Yet, 30 September Stands)

Harsh Vyas
Harsh Vyas CA · Sep 17
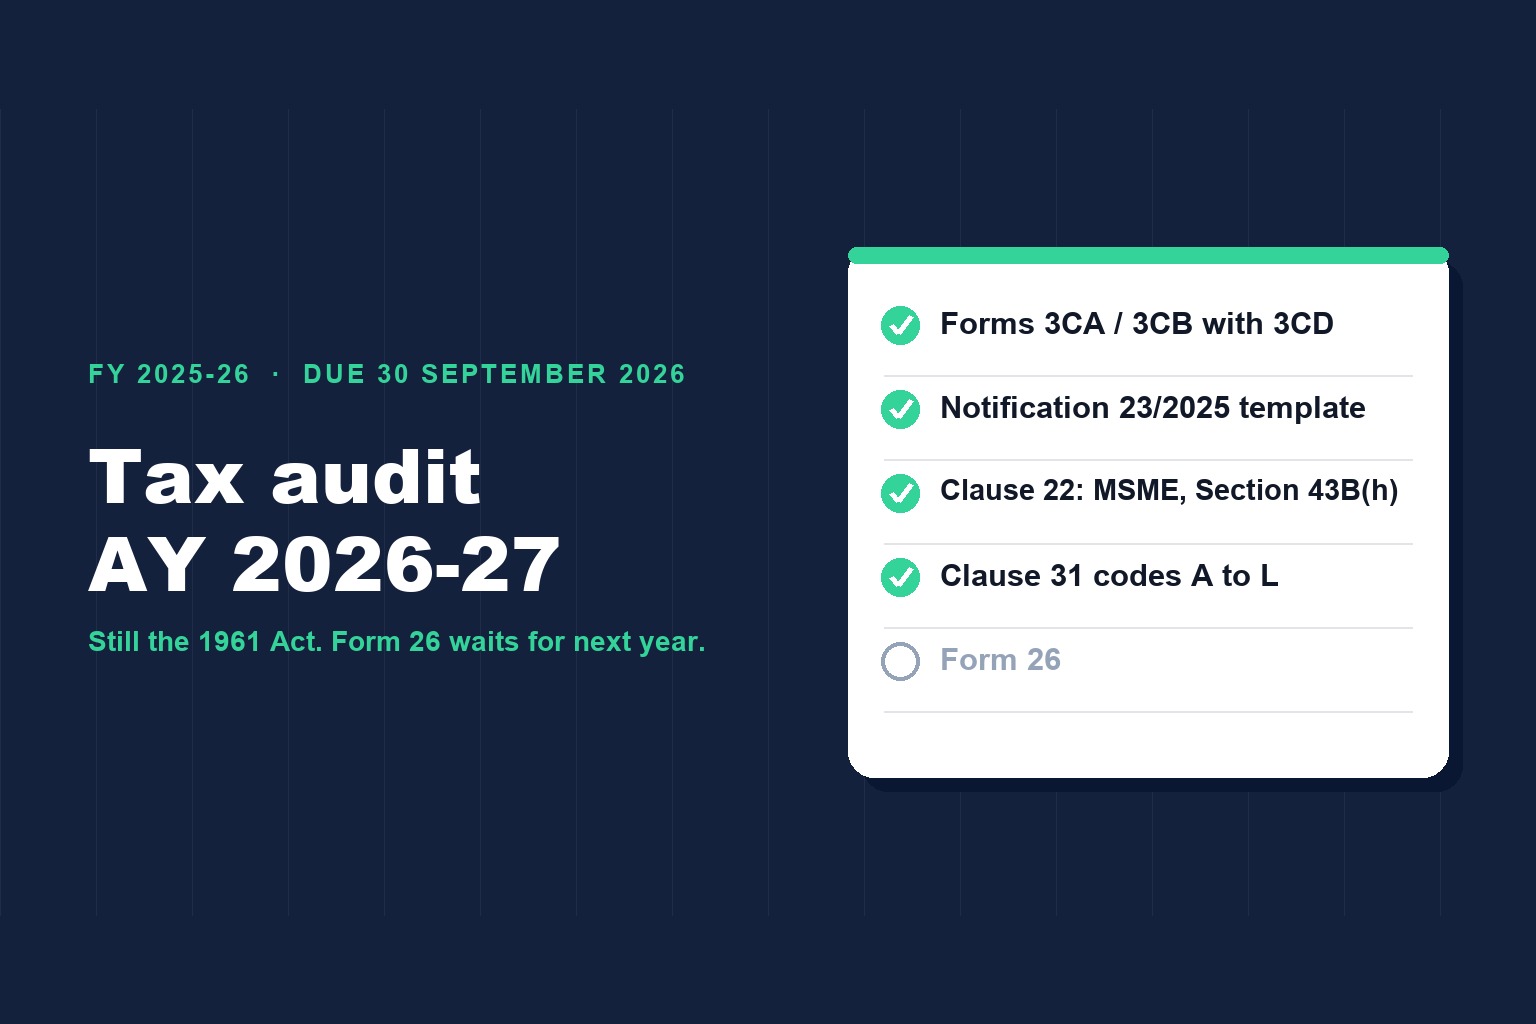
Status as at 17 September 2026: the AY 2026-27 tax audit report is still due 30 September. No CBDT circular under Section 119 has issued. Dated update log, the 2022-2025 extension record with circular numbers, who has asked for what, where a circular appears first, and what a late report costs.

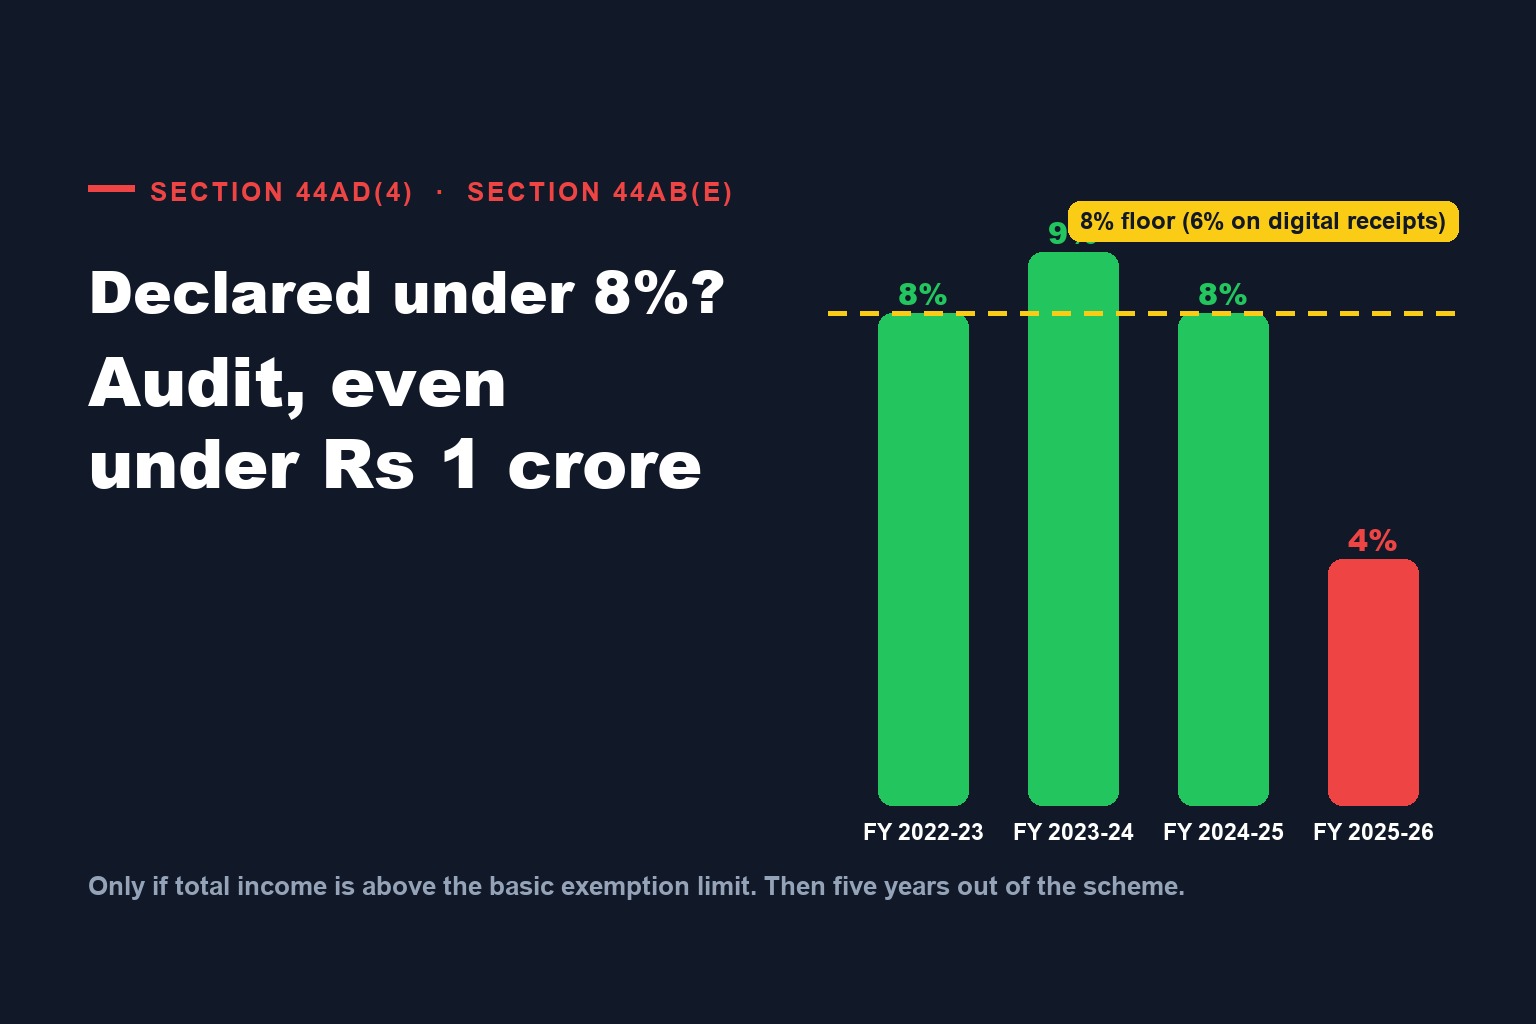
Declared Profit Below 8% or 6%? You May Need a Tax Audit Even Under Rs 1 Crore: The Section 44AD(4) Trap, and Who It Does Not Catch

Vijay R S
Vijay R S · Sep 11
Turnover under Rs 1 crore does not settle the tax-audit question. If you used Section 44AD in any of the last five years and now declare below 8% (6% on digital receipts), Section 44AD(4) applies, and Section 44AB(e) requires an audit when your total income exceeds the basic exemption limit (Rs 4 lakh, new regime). A first-time low-profit declarant who never opted in is NOT caught.

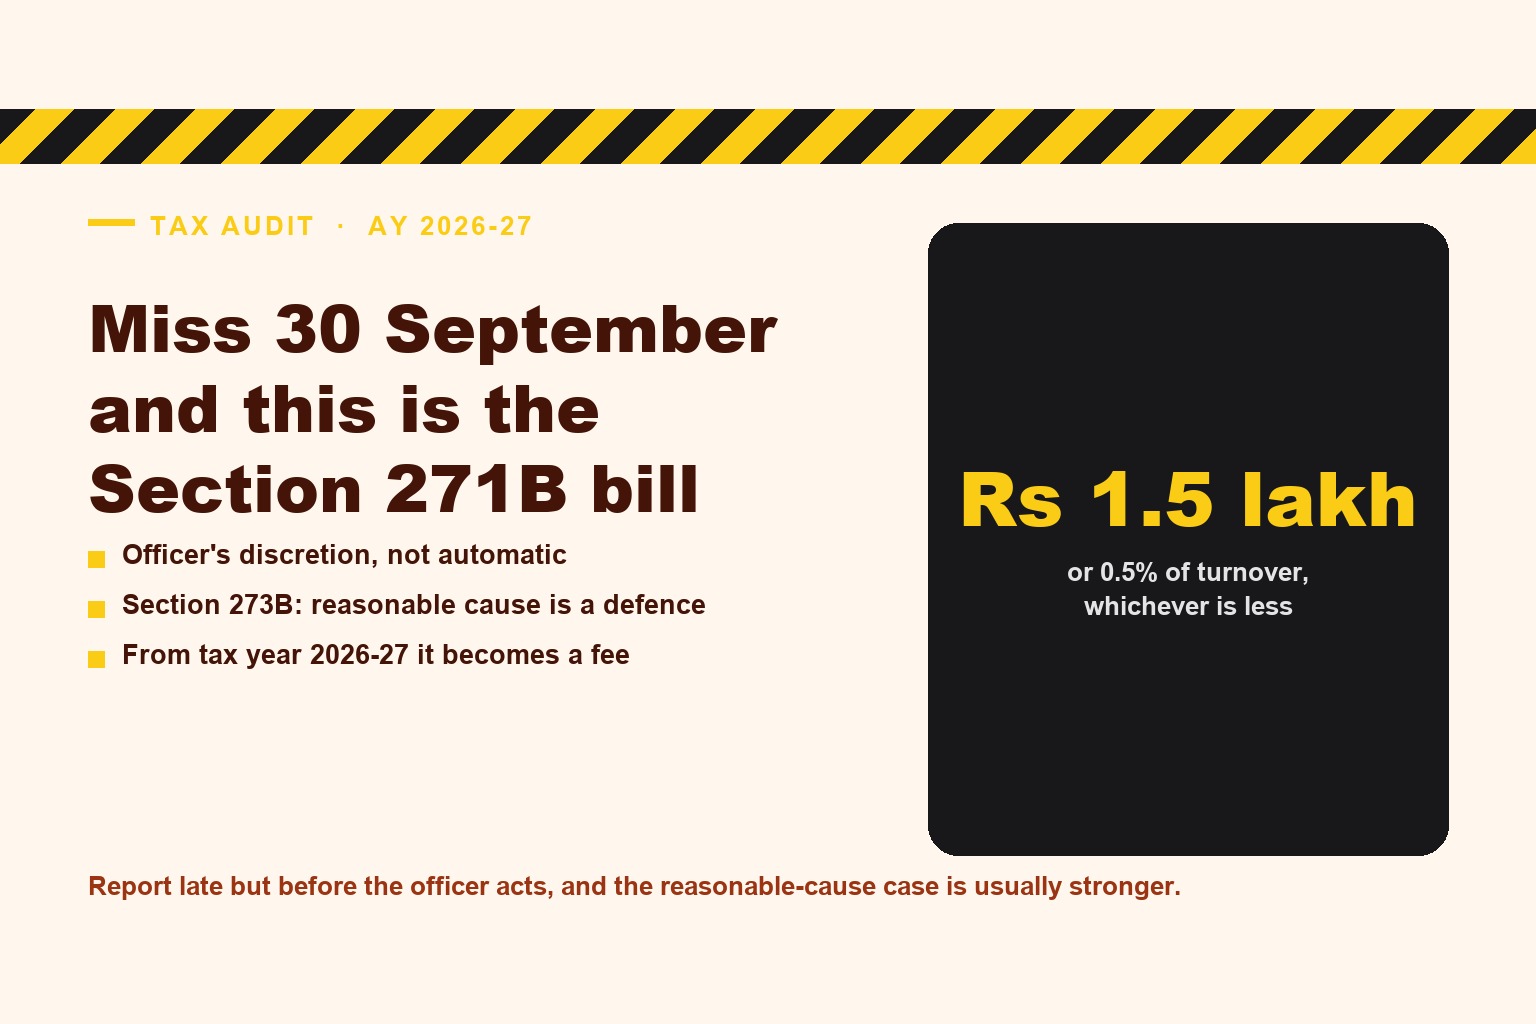
Tax Audit Due Date 30 September 2026: The Section 271B Penalty If You Miss It (0.5% of Turnover, up to Rs 1.5 Lakh), and the Fee That Replaces It Next Year

Vijay R S
Vijay R S · Sep 11
Miss the 30 September 2026 tax-audit date for AY 2026-27 and Section 271B lets the Assessing Officer levy 0.5% of turnover or gross receipts, capped at Rs 1.5 lakh. It is discretionary, and Section 273B waives it for reasonable cause. From tax year 2026-27 the Income-tax Act, 2025 replaces it with a fixed fee: Rs 75,000 for up to a month, Rs 1.5 lakh after.

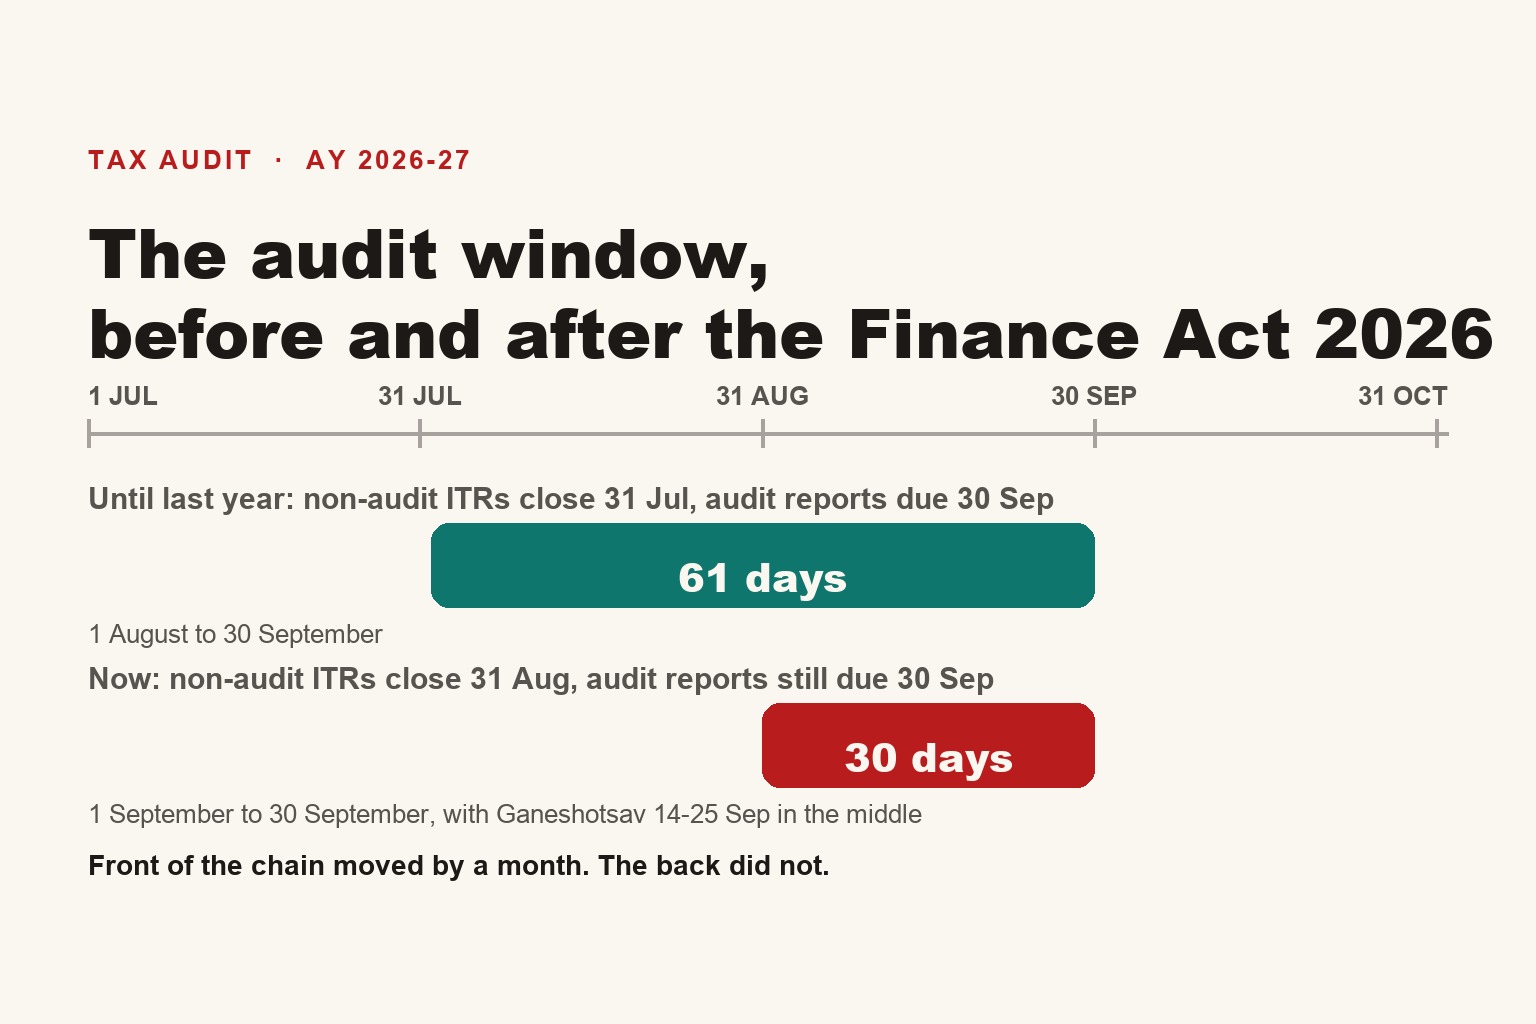
The Finance Act 2026 Cut the Tax Audit Window From 61 Days to 30: Why 30 September Must Move to 31 October, and How to Fix the Law

Harsh Vyas
Harsh Vyas CA · Sep 7
The Finance Act 2026 moved the non-audit business ITR date to 31 August but left the tax audit report at 30 September. The working audit window fell from 61 to 30 days. The September calendar, what CBDT did in 2024 and 2025, and a two-part fix: extend to 31 October now, then re-link the law.

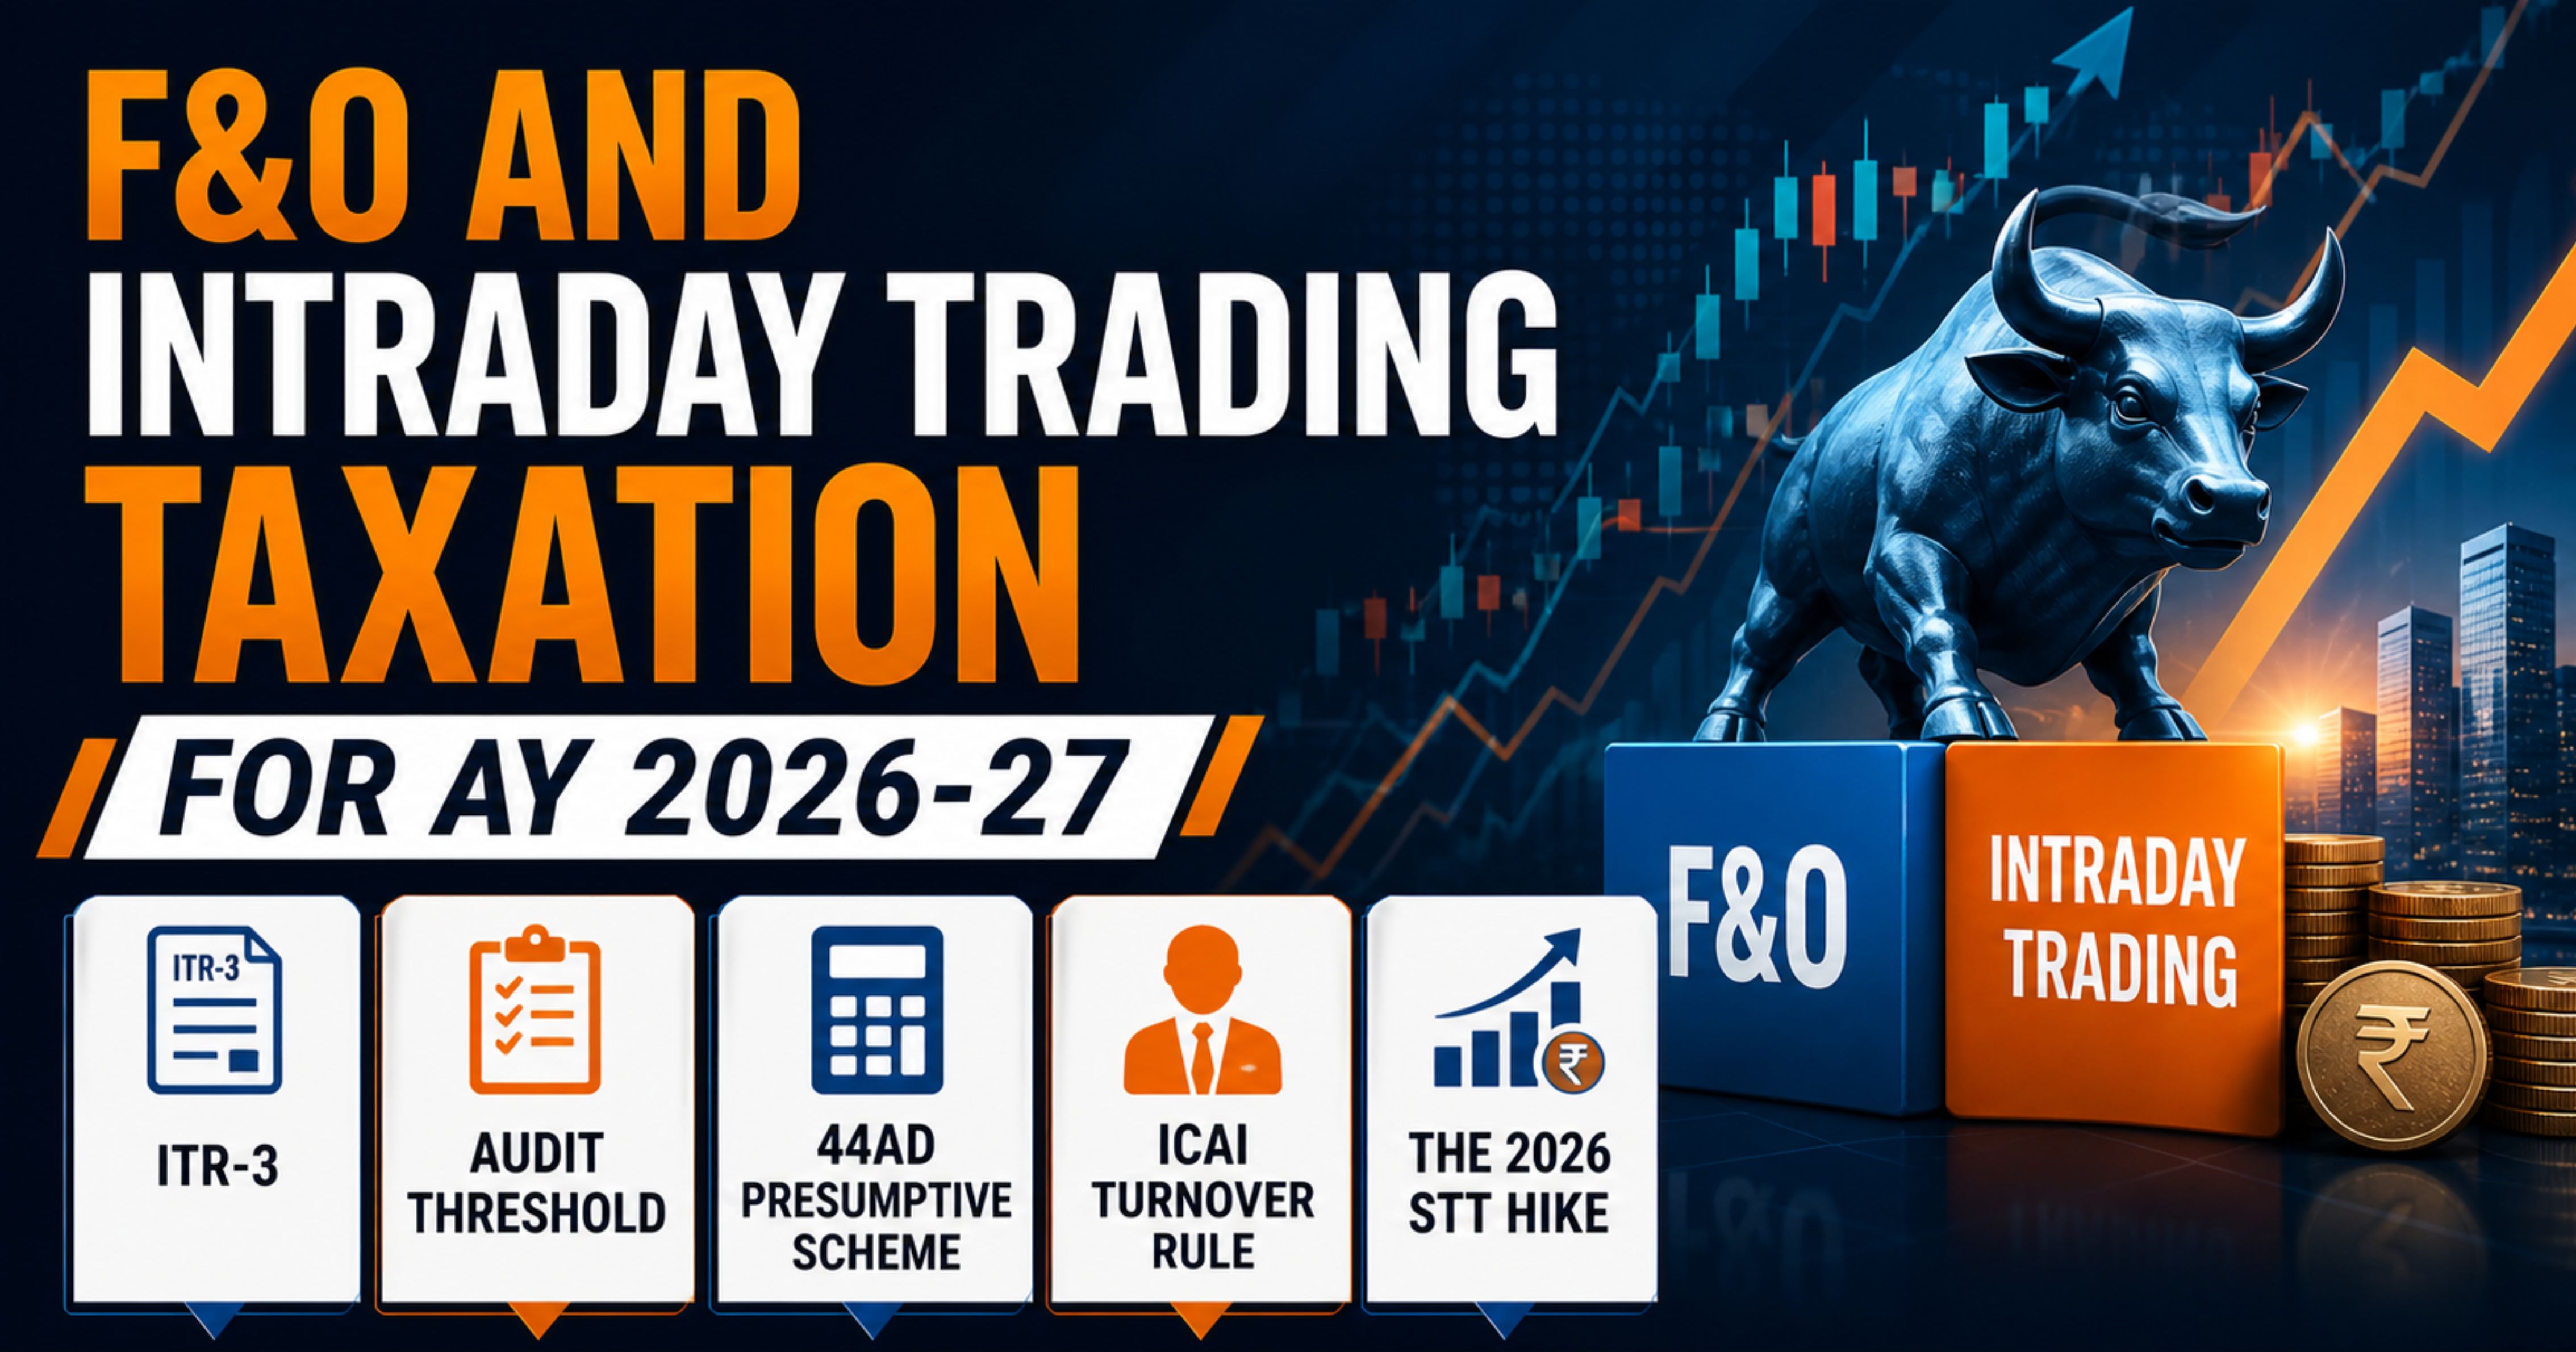
F&O and Intraday Trading Taxation for AY 2026-27: ITR-3, Audit Threshold, 44AD Presumptive Scheme, ICAI Turnover Rule, and the 2026 STT Hike

TaxSocial Editorial Team
F&O = non-spec business; intraday = spec business. File ITR-3. Audit at Rs 10 cr turnover (95% digital). 44AD: 6% digital up to Rs 3 cr. ICAI 8th edition: turnover = absolute P&L. F&O loss carries 8 yrs (Sec 72); intraday loss only against spec gains, 4 yrs (Sec 73).

Freelancer and Gig Worker ITR for AY 2026-27 — Section 44ADA Presumptive Scheme, ITR-3 vs ITR-4 (Sugam), Advance Tax, and Tax Audit Triggers

TaxSocial Editorial Team
Freelancers and gig workers, AY 2026-27. Sec 44ADA presumptive: 50% deemed profit on receipts up to Rs 50L (Rs 75L if cash receipts ≤ 5%). Specified professions only (Sec 44AA(1)) — IT, legal, medical, accountancy etc. ITR-4 (Sugam) for presumptive (total income ≤ Rs 50L); ITR-3 otherwise. Advance tax in one shot by 15 March. Sec 44AB audit if you declare lower than 50% AND income exceeds basic exemption.

Help

Need help? Browse our Help Center for guides on using TaxSocial.

Visit Help Center

View Plans