Harsh Vyas

Harsh Vyas

@hvyas

I'm a Chartered Accountant, and I write here on the GST and income-tax beats. Most of what I cover is what actually comes up across a filing cycle: registration thresholds and the GSTR-1 / 2B / 3B reconciliation chain, input tax credit conditions and reversals under Section 16 and Rule 42/43, e-invoicing turnover limits, TDS and advance-tax mechanics, and the filing decisions that follow from the Income-tax Act 2025 transition. I also write about the financial-modelling side of the job, which rarely gets documented properly — bank project reports and CMA data, provisional and projected financial statements, the ratio covenants lenders actually test, and what makes a projection defensible when a credit officer starts questioning the assumptions. I work from the bare Act, CBIC and CBDT circulars and RBI norms rather than secondary commentary, and I put the numbers in wherever a rule turns on a calculation.

0
Following
5
Followers
17
Articles
2,706
Total views
30
Likes received
Author
Joined Aug 2026
Not verified
  • Credential CA Self-declared, not checked
  • LinkedIn LinkedIn profile Not cross-checked

Areas of specialization

GST, Income Tax, Financial Modelling, Project Reports & CMA Data, Business Projections

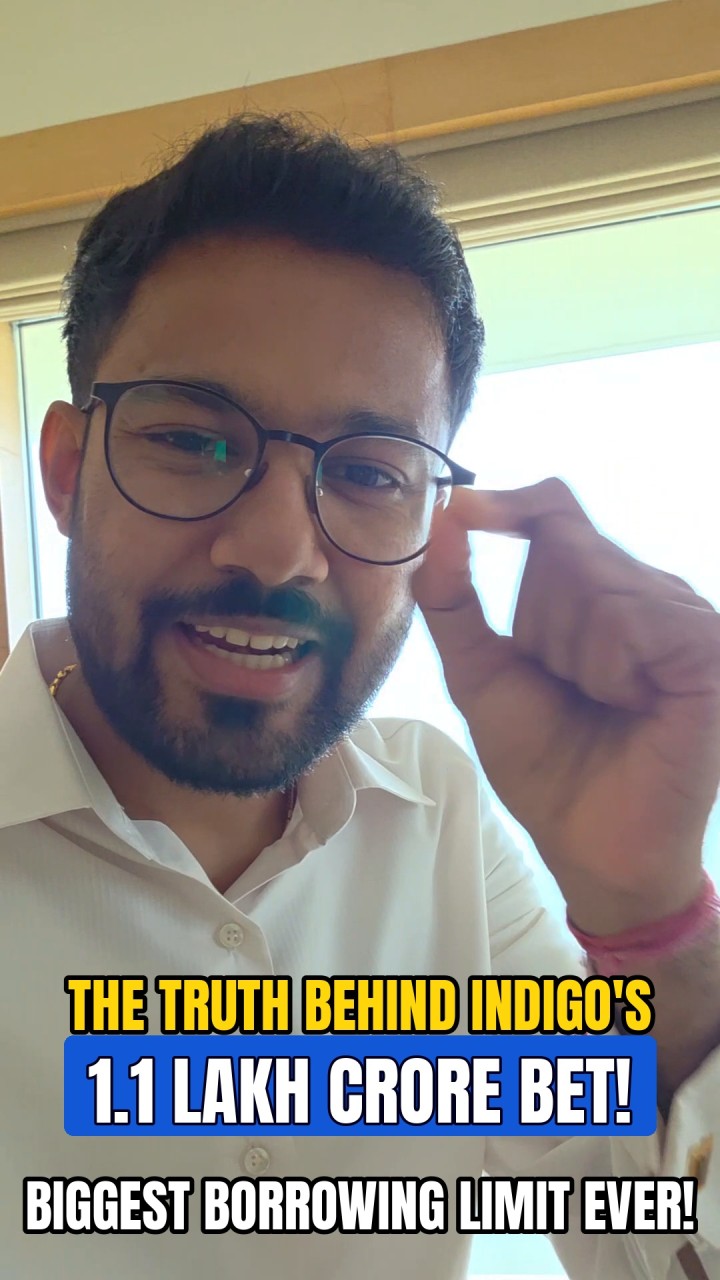
CBIC Issues Circular 266 on GST on Services: R&D Certificate, Shipping Lines, Vehicle Leasing, TRAI, Bank Fund Transfer Pricing and NBFC Co-lending
Harsh Vyas
Harsh Vyas CA · Oct 29
Circular 266/12/2026-GST (28 Oct 2026) settles six services questions: an R&D certificate for grant-funded research, shipping lines' free imports from related persons, vehicle leasing recoveries, TRAI, banks' fund transfer pricing and NBFC co-lending fees. What each answer means.

CBIC Issues Three Circulars on Input Tax Credit: ISD Registration and Reversals, the 50% Option for Banks and NBFCs, and Credit on Demo Cars Under the Agency Model

Harsh Vyas
Harsh Vyas CA · Oct 28
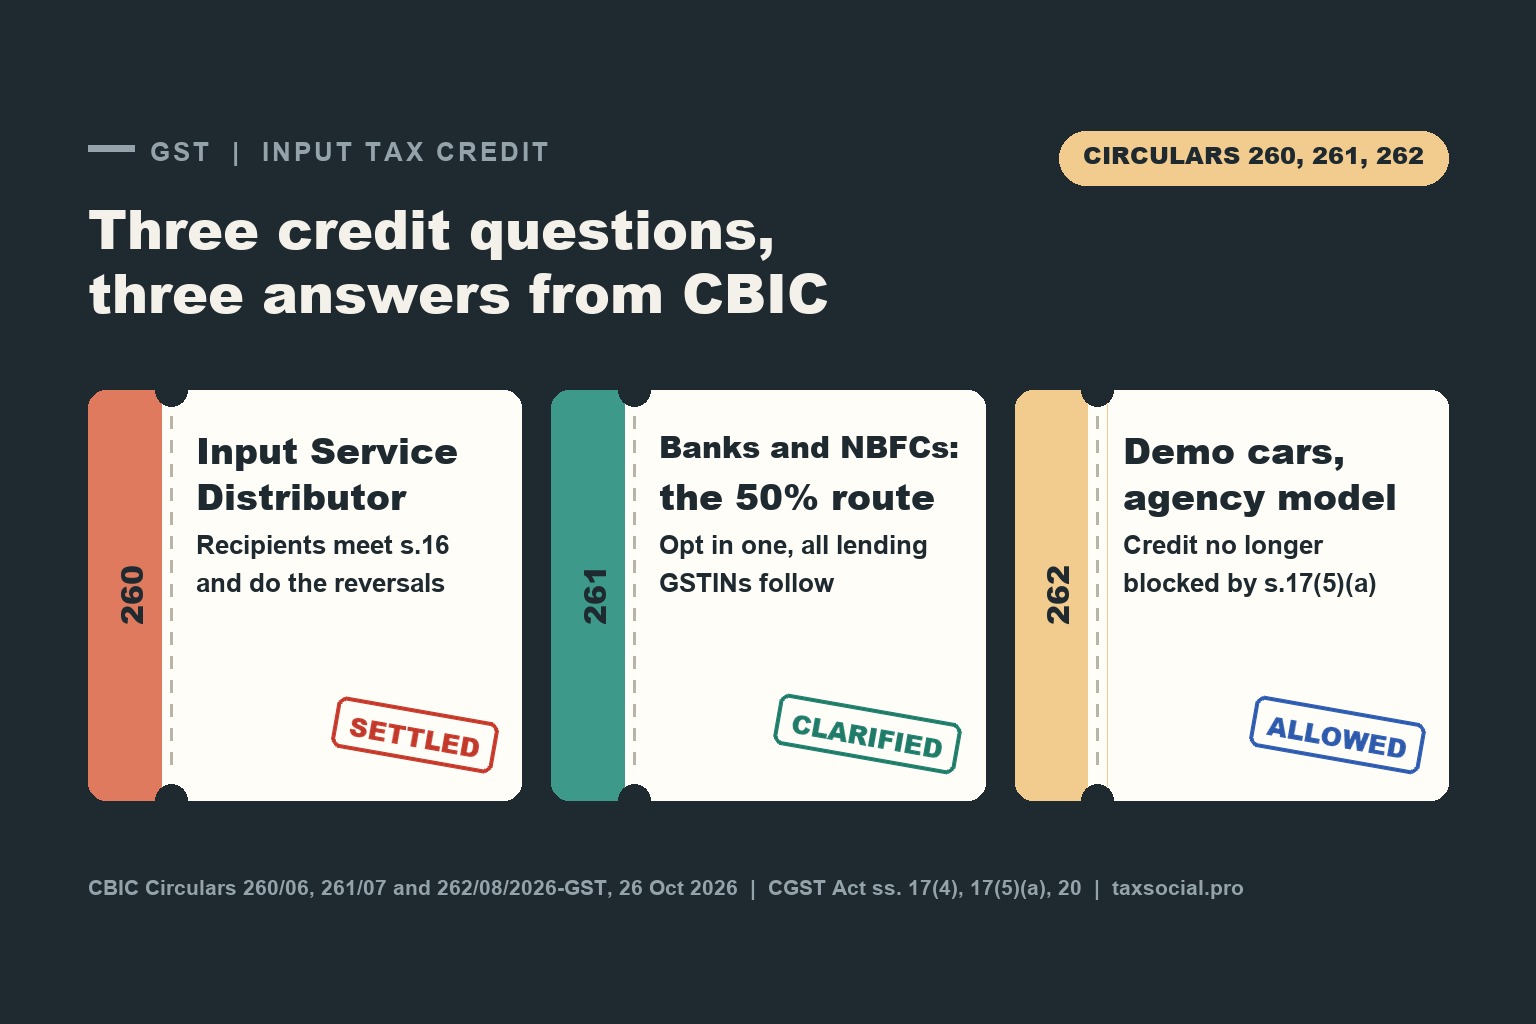
Three CBIC circulars of 26 October 2026 settle input tax credit questions: who must register as an ISD and who reverses distributed credit, which bank and NBFC registrations can take the 50% option and how to report it in GSTR-3B, and why demo car credit under the agency model is no longer blocked.

NFRA Recommends Ind AS 118 from 1 April 2027 (Awaiting MCA Notification): Operating Profit, Expenses by Function, MPMs and What Companies Must Change

Harsh Vyas
Harsh Vyas CA · Oct 26
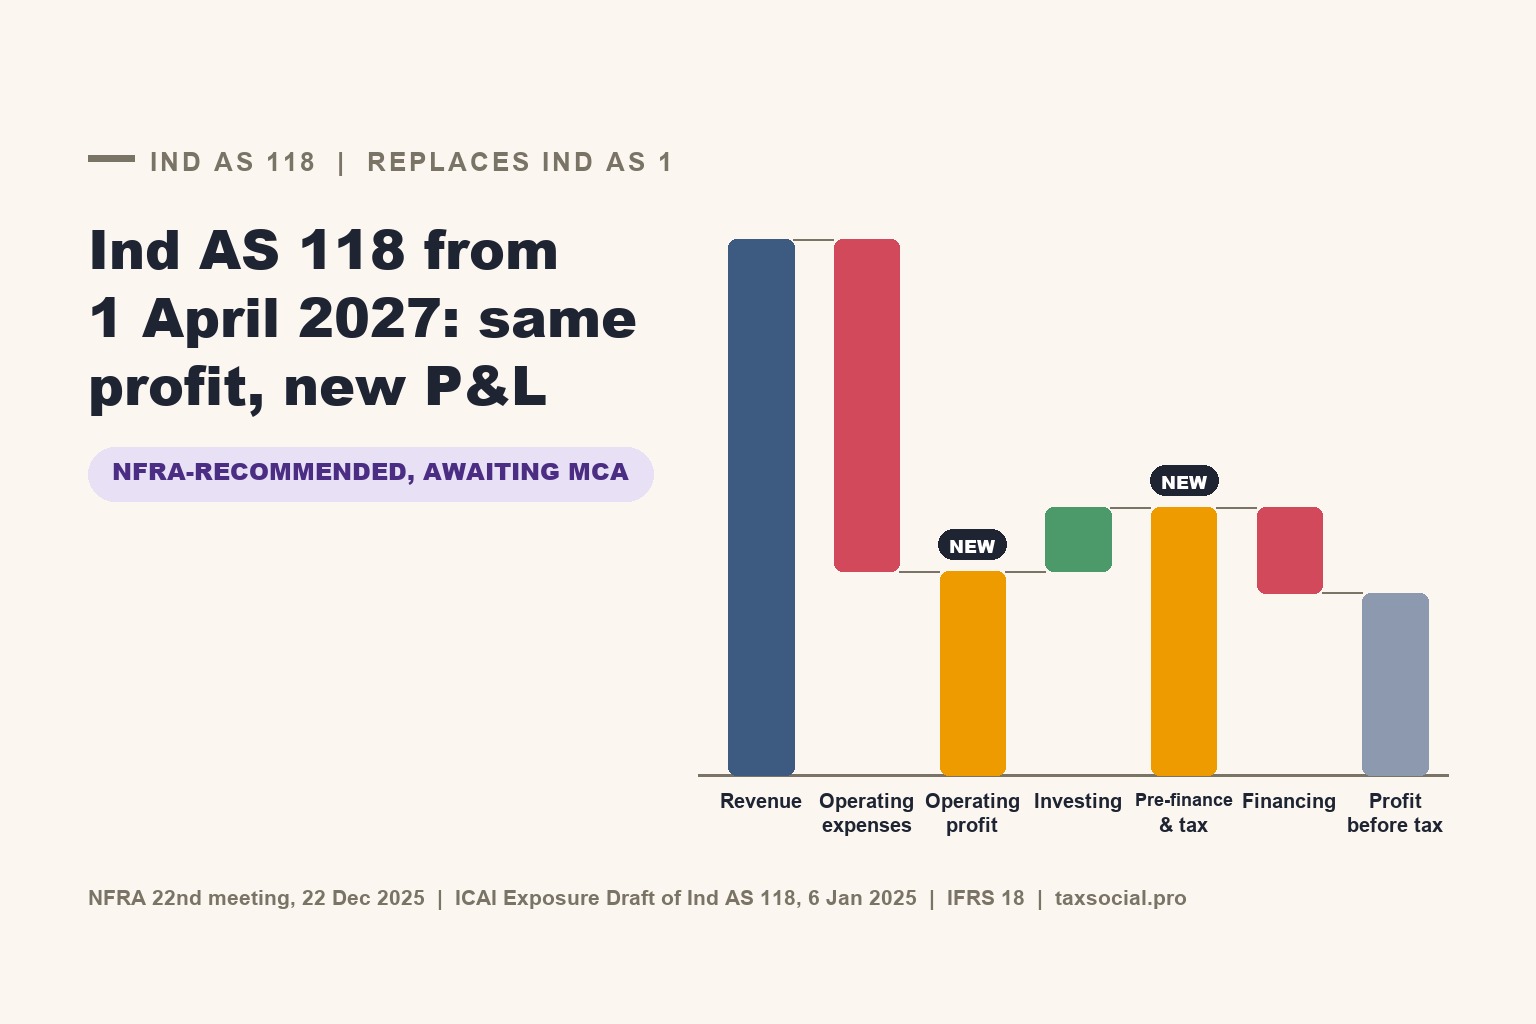
Ind AS 118 will replace Ind AS 1 from 1 April 2027 if MCA notifies it as NFRA recommended. Profit does not change; the P&L layout does: five categories, operating profit, expenses by function as an option, and audited notes on adjusted measures. Restated FY 2026-27 comparatives mean work starts now.

ICAI Issues Guidelines on Tenders for CAs in Practice: No Bid Without a Minimum Fee, No "Extremely Low" Quotes, Cost Sheet Mandatory

Harsh Vyas
Harsh Vyas CA · Oct 13
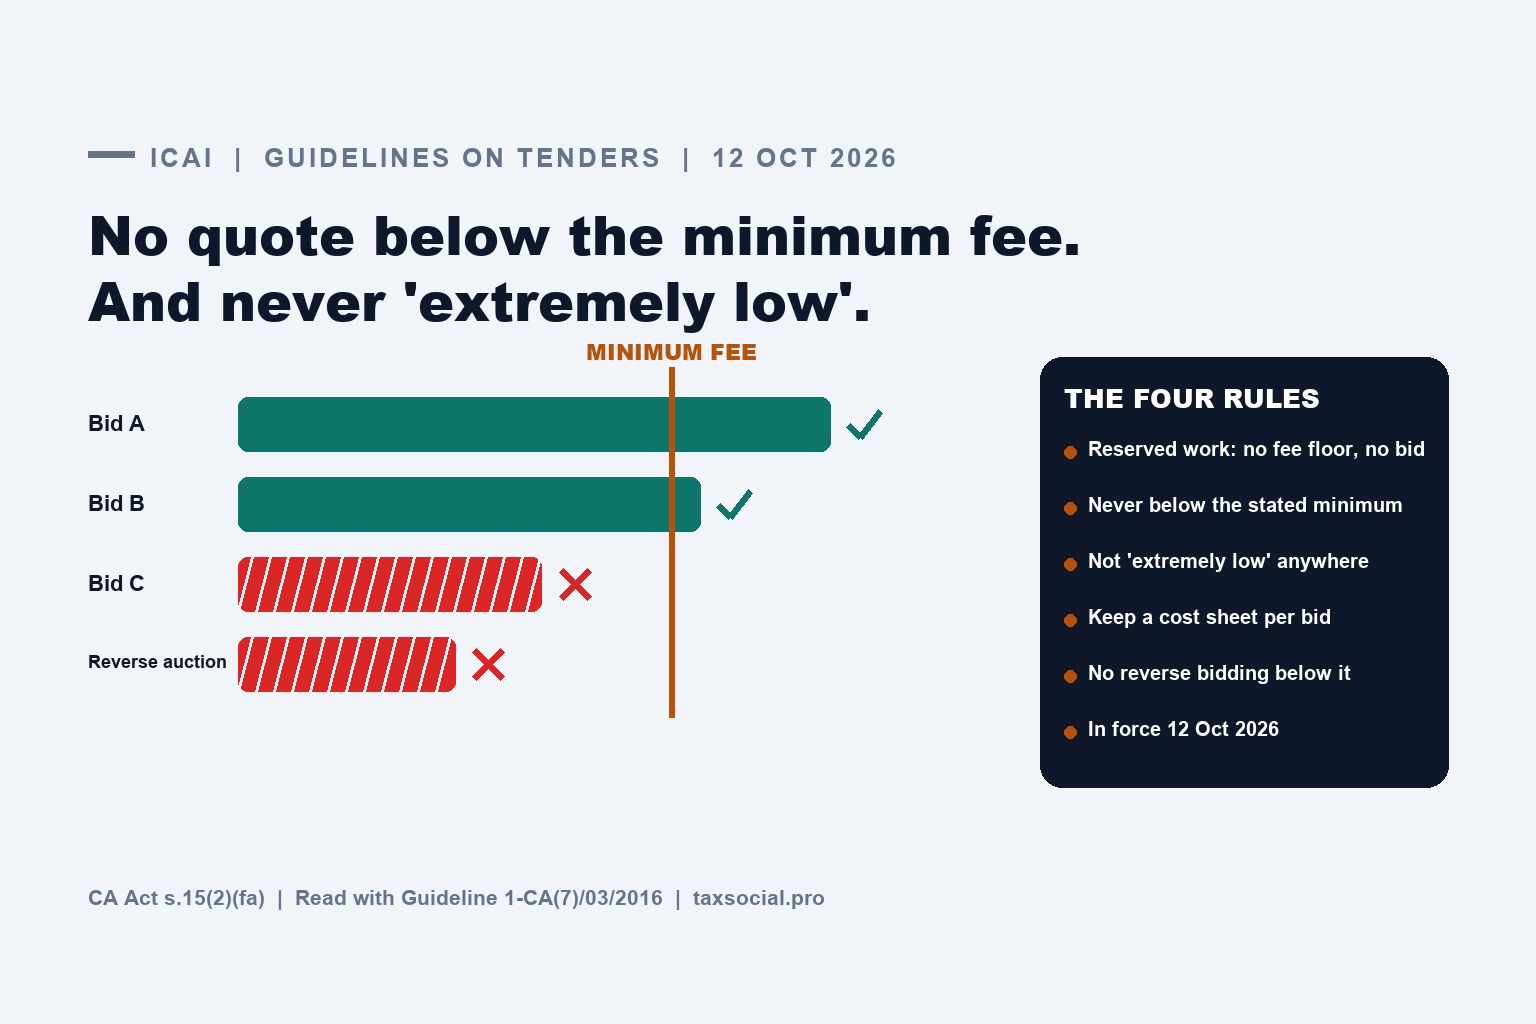
ICAI issued guidelines on tenders for members in practice on 12 October 2026: no response to tenders for statutorily reserved work without a minimum fee, no quote below it or in a reverse auction, no extremely low fees for any work, and a cost sheet for every bid. What is new since 2016.

ICAI's Plan to Build India's Own Big Four: What Is Actually on the Table, What a Mid-Sized CA Firm Can Already Do, and the Consulting Tender Rules Changing First

Harsh Vyas
Harsh Vyas CA · Oct 2
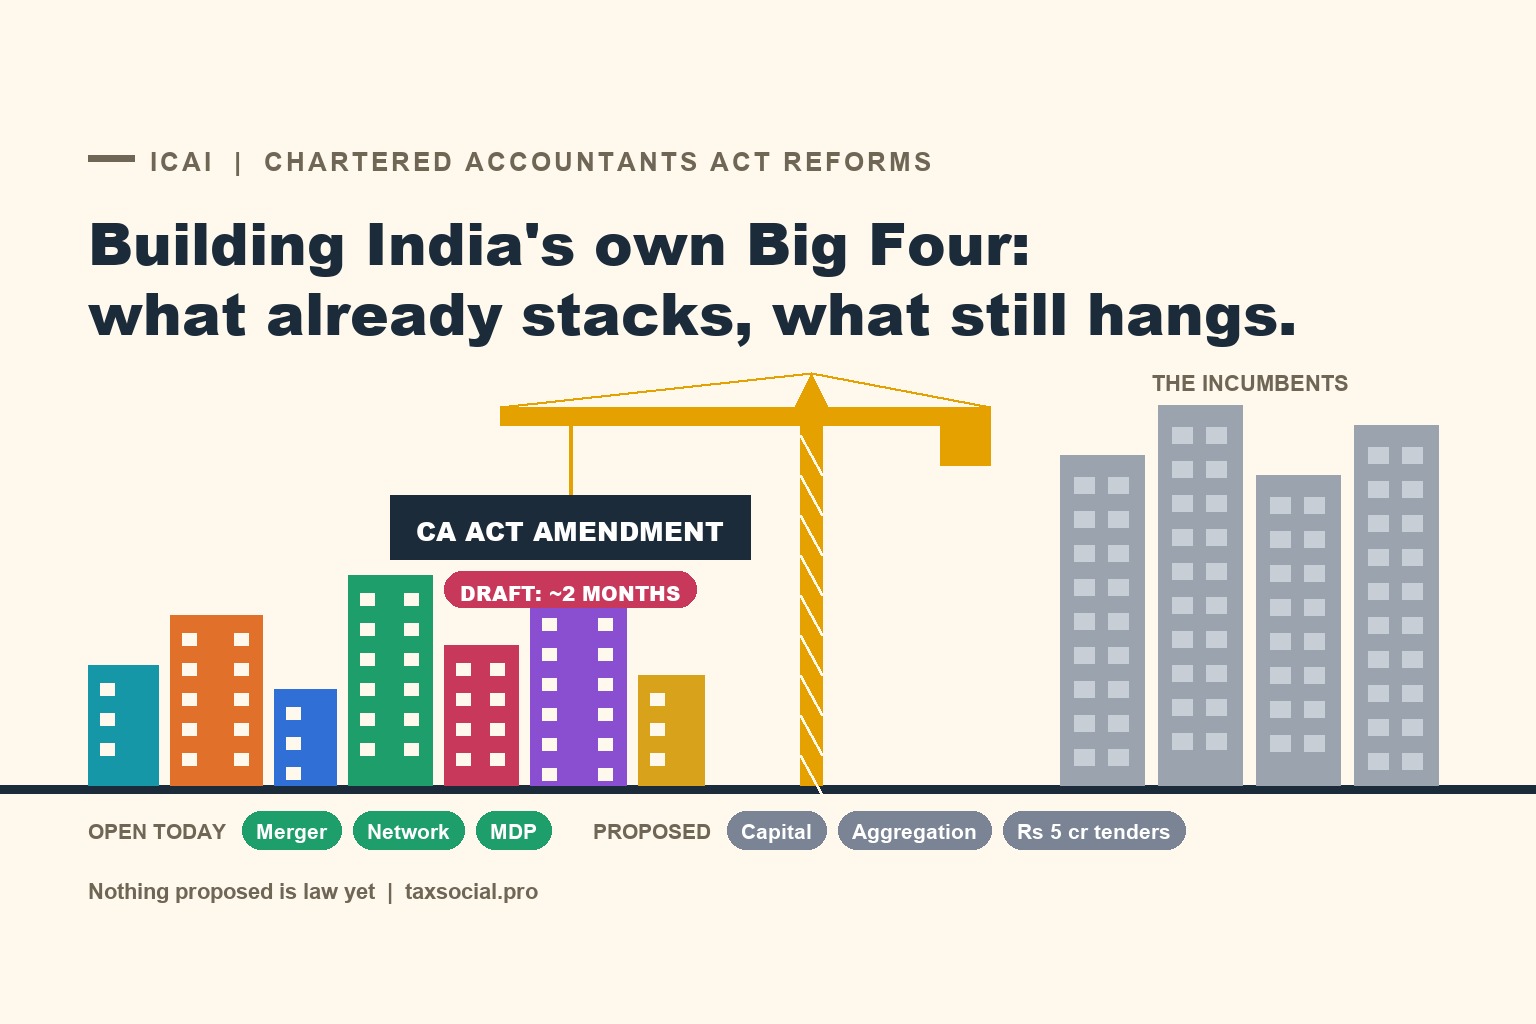
ICAI says a draft of CA Act changes to help Indian firms scale up will be ready in about two months. Nothing is law yet. Here is what has been proposed, what the rules already let a small firm do (merge, network, form an MDP), and the government tender change that matters sooner.

Help

Your public profile. Edit your details, choose what to show, verify your website for free, and request institute verification with Pro.

Visit Help Center

View Plans