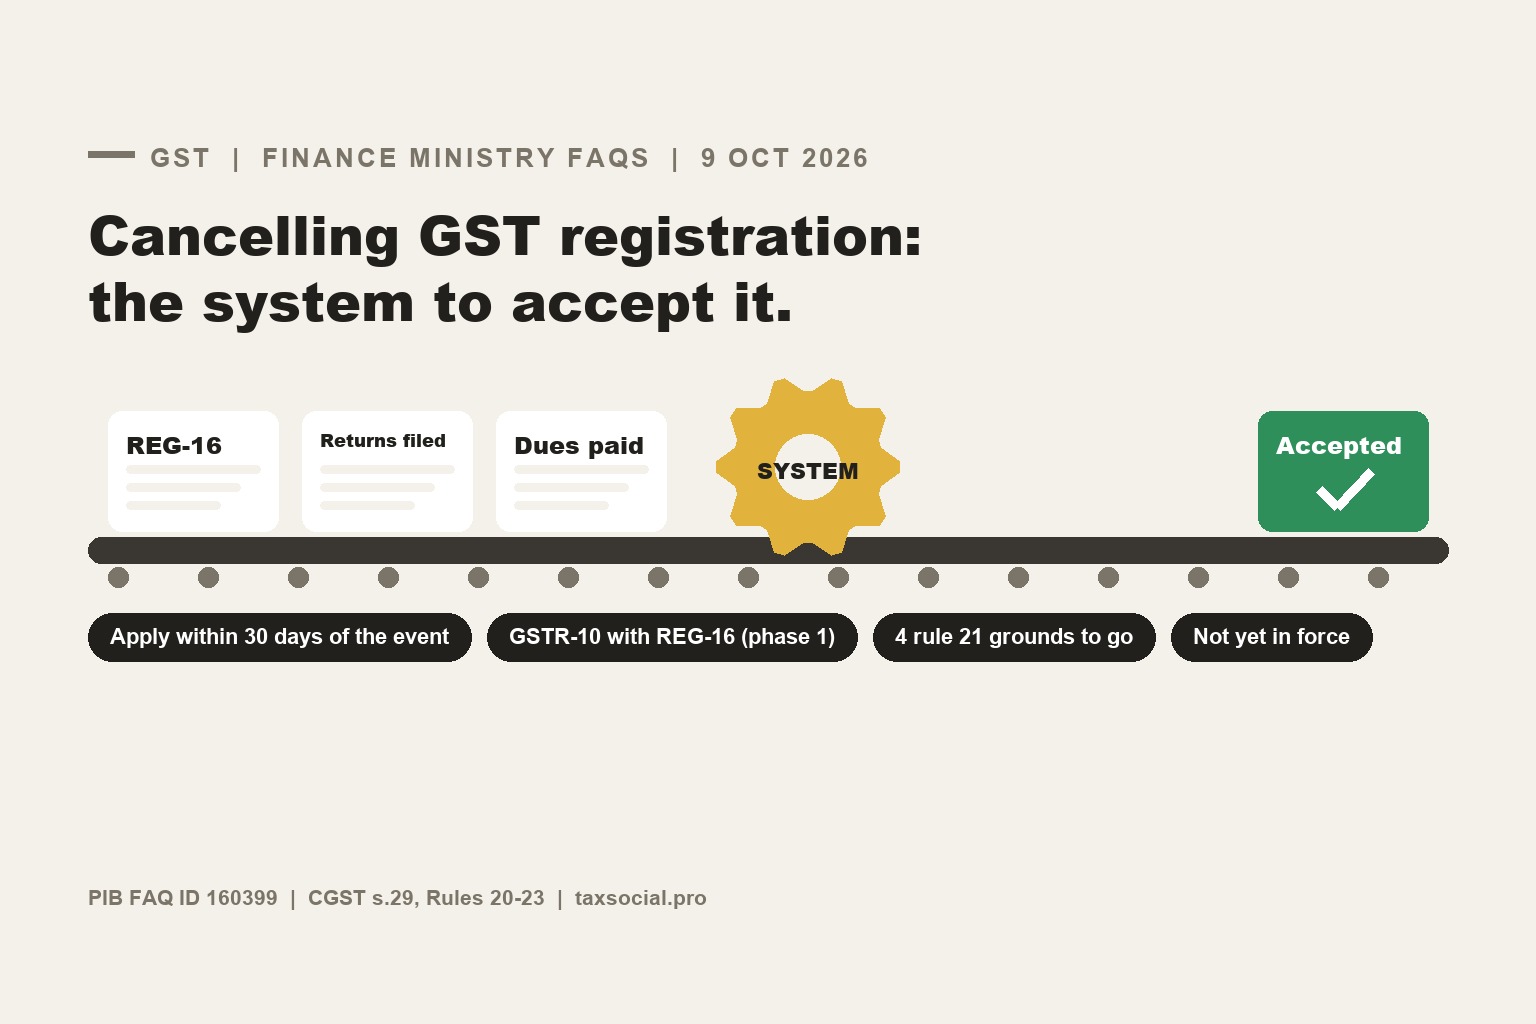

On 9 October 2026 the Finance Ministry published eight FAQs on cancellation of GST registration on the Press Information Bureau site, the day after the 57th GST Council meeting. They explain how cancellation will work once the Council's recommendations are in force. Applications in FORM GST REG-16 are to be accepted automatically by the system once all returns are filed and dues paid. Registrations suspended for non-filing or for missing bank details are to be cancelled, and revoked, by the system. And four grounds on which an officer can cancel registration are to go from rule 21. Read them as a description of the new system, not the law today. Most of it needs rule changes, and the system cancellation needs section 29 amended. Until then, an officer still decides your REG-16 under rule 22. The FAQs are attached to this article, and the full text is on pib.gov.in (FAQ ID 160399).
1. When you can apply, and the 30-day limit
FAQ 1 lists the familiar grounds: the business has been discontinued, closed or fully transferred; a change in constitution that results in a new PAN; amalgamation, demerger or disposal; or you are no longer liable to be registered. These broadly track section 29(1) of the CGST Act, which speaks of "any change in the constitution of the business" without requiring a new PAN.
FAQ 3 says you should apply within 30 days of the event that warrants cancellation. That is rule 20 as it stands: the REG-16 is to be filed "within a period of thirty days of the occurrence of the event warranting the cancellation". The FAQ adds one exception: on the death of a sole proprietor, "there is no such time limit". Rule 20's 30 days are written for "a registered person" seeking cancellation. Section 29(1) separately lets legal heirs apply on death, and rule 22(5) applies the cancellation order to them, but rule 20 does not expressly set a deadline for their application. The FAQ reads that gap as no time limit. An FAQ does not amend the rules, so heirs should still apply promptly.
2. How to apply
FAQ 2 describes the steps on the portal, which are unchanged:
- Log in at gst.gov.in and go to Services > Registration > Application for Cancellation of Registration (FORM GST REG-16).
- Give the reason, the date from which you want the cancellation, the closing stock (inputs, inputs in semi-finished and finished goods, and capital goods) and the tax on it. Rule 20 asks for exactly these details.
- Verify with a DSC or EVC and submit. An ARN is generated, and the status can be tracked on the portal.
3. Automatic acceptance: the conditions
FAQ 4 sets three conditions for auto-acceptance of a REG-16:
- All returns due on or before the date of the application have been furnished.
- Any tax, interest or penalty due has been paid, unless it has been stayed by a court, the Tribunal or an appellate authority.
- If you filed GSTR-1 or IFF for a tax period, you must file GSTR-3B for that period before applying. A period with outward supplies reported but no return filed will block auto-acceptance.
Who gets it, and when, depends on the credit you have passed on to buyers:
| Your situation | Phase 1 | Phase 2 |
|---|---|---|
| Never passed on credit above Rs 2.5 lakh in any month since registration (FAQ 5) | Accepted automatically once the conditions are met; communicated on the portal in FORM GST REG-38 | |
| Passed on credit above Rs 2.5 lakh in any month (FAQ 6) | Automatic if you file REG-16 together with the final return in GSTR-10 | Only REG-16 needed; REG-16 is to be amended to carry the GSTR-10 details |
Compare today. Rule 22(3) has the proper officer pass an order in FORM GST REG-19 within thirty days of the REG-16 application (or of the reply to a show cause notice, where one was issued), cancelling the registration from a date he decides. The final return in GSTR-10 is filed separately afterwards, within three months of the date of cancellation or of the cancellation order, whichever is later. The FAQs do not give dates for phase 1 or phase 2.
4. Suspension, system cancellation and revocation
FAQ 7 deals with a registration the system has suspended for one of two defaults: not filing returns for six consecutive months, or not furnishing bank account details under rule 10A. The FAQ says section 29 is being amended so that such a registration can be cancelled by the system, without an officer. And if you then comply and apply for revocation in FORM GST REG-21 within 180 days of the date of cancellation, the system will revoke the cancellation.
Two differences from today are worth noticing. At present, an officer cancels after a show cause notice in REG-17 and your reply in REG-18 (rule 22). And under rule 23 a revocation application is due within 90 days of service of the cancellation order, extendable, on sufficient cause and for recorded reasons, by the Commissioner or an authorised officer not below Additional or Joint Commissioner for up to 180 days more; an officer decides it. The FAQ's 180 days runs from the date of cancellation, and the revocation is by the system. Both need the Act and the rules amended before they apply.
5. Four grounds for cancellation by the officer to go
FAQ 8: the Council recommended omitting four grounds from rule 21. The current text of rule 21, and what happens to each ground:
| Rule 21 | Ground | Recommended |
|---|---|---|
| (a) | No business from the declared place of business | Stays |
| (b) | Invoice or bill issued without supply | Stays |
| (c) | Violation of section 171 (anti-profiteering) | Omitted |
| (d) | Violation of rule 10A (bank account details) | Stays. The recommended system cancellation (FAQ 7) would apply to this default once in force |
| (e) | Input tax credit availed in violation of section 16 | Omitted |
| (f) | Outward supplies in GSTR-1, as amended in GSTR-1A, in excess of those in the valid section 39 return (GSTR-3B) for the period | Omitted |
| (g) | Violation of rule 86B (the 1% cash payment rule) | Omitted |
| (ga) | Violation of the third or fourth proviso to rule 23(1) | Stays |
| (h), (i) | Returns not filed for six months (monthly) or two tax periods (quarterly) | Stays. The recommended system cancellation (FAQ 7) would apply to this default once in force |
The four that go are the ones most often used against businesses with a mismatch or a disputed credit, as opposed to outright fake invoicing. Wrong credit and a GSTR-1/GSTR-3B gap can still be pursued as a demand under sections 73, 74 or 74A. What goes is cancellation of the registration as the remedy. Fake invoicing, under clause (b), stays a ground.
6. What the FAQs do not tell you
- Dates. The FAQs read as if the new system is in place ("will be accepted automatically", "section 29 is being amended"). It is not. They follow the Council's recommendations of 8 October, which "would be given effect through the relevant circulars/ notifications/ law amendments which alone shall have the force of law".
- REG-38. The form in which auto-acceptance is communicated is named as FORM GST REG-38. The current cancellation order is REG-19; expect the amended rules to set out the new form.
- Liability survives. Section 29(3) is untouched: cancellation does not end liability for tax and dues for the period before cancellation, whether determined before or after. Auto-acceptance does not change that.
- Section 29(5). On cancellation you still pay an amount equal to the credit on inputs and capital goods held in stock on the day before cancellation, or the output tax on them, whichever is higher. For capital goods, the credit is reduced by the prescribed percentage points or the tax on transaction value is taken, whichever is higher. That is why REG-16 asks for closing stock.
7. What to do now
- Closing a business now: file REG-16 within 30 days of the event, as rule 20 requires. An officer will process it as today.
- Planning to close in the next few months: clear the backlog first. Every return due, every GSTR-3B for a period where GSTR-1 was filed, and all undisputed dues. That is what auto-acceptance will need. Today, clearing dues is not a stated precondition; the officer's REG-19 order directs payment of arrears, including the section 29(5) amount, but a clean record avoids a show cause notice.
- If you have passed on more than Rs 2.5 lakh of credit in any month: have the GSTR-10 figures ready to file with the application.
- If you have a pending show cause notice under rule 21(c), (e), (f) or (g): reply on the merits. The ground still exists until rule 21 is amended. Do mention the Council's recommendation in your reply.
The other decisions of the meeting are in our 57th GST Council roundup, and the registration changes for small businesses are in our small business article.
Source: "Frequently Asked Questions (FAQs) on cancellation of GST registration", Ministry of Finance, Press Information Bureau, 9 October 2026, 5:01 pm (FAQ ID 160399), attached; Recommendations of the 57th Meeting of the GST Council, PIB, 8 October 2026 (Release ID 2320934), item 3; CGST Act sections 29 and 30; CGST Rules 20, 21, 22 and 23 as in force.

Comments (0)
No comments yet. Be the first to comment!