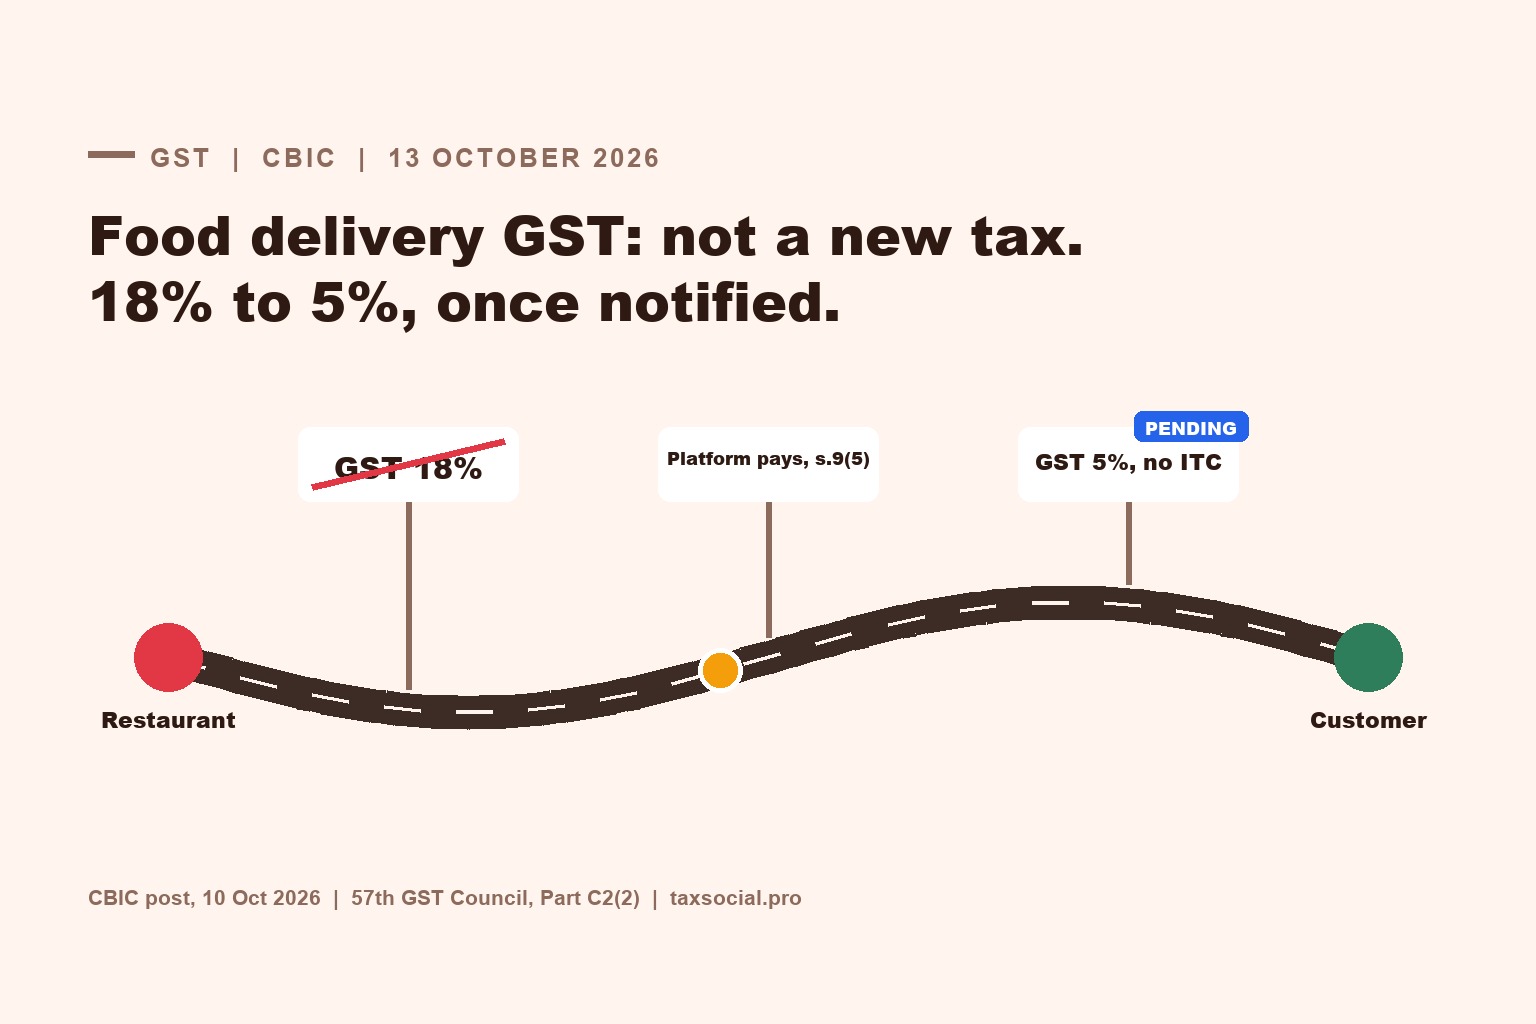
CBIC is right that there is no new tax. On 10 October 2026 it posted, in reply to a viral claim of a "new GST" on food delivery: "Delivery services, for example those provided by food apps, were earlier taxed at 18%. The tax on these delivery services has now been reduced to 5%". The reduction comes from the 57th GST Council (8 October), which recommended 5% without input tax credit on delivery services linked to e-commerce platforms, paid by the platform where the delivery partner is not required to register. But the 5% is a recommendation until the rate notification is issued. As at 13 October 2026, the latest Central Tax (Rate) notification on CBIC's tax information portal is 01/2026, of May. Until a new one is issued, the existing 18% applies. This article sets out what was taxed before, what changes, who pays, and what to look for in the notification.
1. What CBIC said, and what it was answering
A post circulated on social media claiming the government was imposing a new GST on food delivery. CBIC replied on X on 10 October 2026 that the claim was "wrong and factually incorrect": delivery services, such as those of food apps, "were earlier taxed at 18%", and "the tax on these delivery services has now been reduced to 5% as recommended in the 57th GST Council meeting".
The first half is plainly right. Delivery was already taxed, and the Council's recommendation lowers the rate. The second half, "has now been reduced", needs care. A Council recommendation changes nothing until the Government issues a rate notification. CBIC's own tax information portal lists no new Central Tax (Rate) notification since 01/2026. So the honest reading is: the reduction has been recommended; it takes effect from the date the notification says.
2. How delivery is taxed today
- Delivery services are taxable at 18%. A delivery charge on an app bill is a supply of service, not part of the food.
- Since 22 September 2025, local delivery through an e-commerce operator is under section 9(5). Notification 17/2025-Central Tax (Rate), issued on the 56th Council's recommendation, added local delivery services to the list of services on which the e-commerce operator pays the tax "as if he is the supplier", unless the person actually supplying through the platform is liable to register under section 22(1). Whether a gig delivery partner is liable depends on his aggregate turnover against the threshold, not on his earnings from one app; most are not. Where he is not, the platform pays GST on his service, and it must pay that tax in cash, not out of its input tax credit (CBIC Circular 167/23/2021-GST). (Our reverse charge article explains why section 9(5) is not "reverse charge" in the technical sense.)
- Restaurant food ordered through an app is a separate supply. Restaurant service other than at "specified premises" (in effect, hotels with room tariffs above Rs 7,500) is under section 9(5) at 5% without credit, with the platform paying; restaurant service at specified premises is excluded from section 9(5) and taxed at 18% with credit. None of that changes.
3. What the 57th Council recommended
Part C2, item 2 of the Council's press release of 8 October 2026, explained in the Finance Ministry's FAQs on services of 9 October (FAQs 12 to 17):
| Service | Recommended | Who pays |
|---|---|---|
| Delivery services (other than courier and postal) supplied through an e-commerce operator, where the delivery person is not liable to register | 5% without ITC | The e-commerce operator, under section 9(5) |
| The same, where the delivery service provider is liable to register | 5% without ITC | The delivery service provider |
| Delivery services in relation to goods supplied or ordered through an e-commerce operator (other than courier and postal) | 5% without ITC | The supplier of the delivery service |
| GTA transport of goods ordered through an e-commerce operator, to unregistered persons | Exemption under entry 21A withdrawn; 5% without ITC or 18% with ITC | The GTA (not the platform; FAQ 13) |
Two points from the FAQs are easy to miss. First, the GTA change goes the other way: GTA transport of goods for unregistered buyers was exempt under entry 21A of Notification 12/2017-CT(R), and for goods ordered through a platform that exemption is to go. Second, FAQ 17 says individual truck owners and operators are not affected.
4. What it means for a customer's bill
Take a delivery charge of Rs 40. At 18%, the GST on it is Rs 7.20. At 5%, it is Rs 2. The difference is a little over Rs 5 an order, and only on the delivery charge, not on the food. Whether customers see it depends on the platform. The tax is the platform's liability where it pays under section 9(5), so it is the platform that decides whether the delivery fee shown to the customer comes down.
Where the platform pays under section 9(5) for an unregistered delivery partner, the change is close to a straight rate cut: that tax is paid in cash anyway, so the platform's own input credits were never used to discharge it. "Without ITC" matters more to registered delivery companies, which pay the tax themselves and lose credit on their own costs at the 5% rate.
5. Questions readers are asking
- Will my food bill come down? Only the GST on the delivery charge changes, from 18% to 5% once notified. The GST on the food itself is a separate supply and does not change. Whether the platform passes the saving on in the delivery fee is up to the platform.
- Does it cover grocery and quick-commerce deliveries? The release covers delivery services "in relation to goods supplied/ordered through an ECO", not only food. FAQ 15 puts that delivery at 5% without ITC.
- What about courier and postal services? They are expressly excluded. Courier services stay at their existing rate.
- What about the platform fee or convenience fee? The recommendation is about delivery services. It says nothing about a platform's own fees, which are a separate service and are not affected by this change.
- Is anything new being taxed? No. Delivery has been taxed all along. What CBIC called false was the claim of a new tax; what it described is a lower rate.
6. What to look for in the notification
- The date. The 5% applies from the date the notification gives. Until then, 18% applies. For supplies that straddle the change, section 14 decides the rate by looking at when the service was supplied, when the invoice was issued and when payment was received; an invoice dated before the change does not always mean 18%.
- The definition of "delivery services". Whether it covers only last-mile delivery to the customer, or also pickup and hub-to-hub movement, and how it separates delivery from courier services.
- The section 9(5) entry. The current entry, inserted by Notification 17/2025, says "local delivery services". The new one may change the wording.
- The GTA change to entry 21A, which affects logistics firms carrying platform orders.
7. For platforms, delivery partners and logistics firms
- Platforms: keep paying 18% under section 9(5) on delivery until the notification is out, then change the rate from its effective date. Where the platform itself supplies delivery (for instance through registered fleets), check the effect of the without-ITC condition on its own credits.
- Delivery partners below the threshold: nothing changes for you. The platform pays, as it has since September 2025.
- Registered delivery companies: you will pay 5% without ITC on delivery linked to platform orders. Check whether that is better or worse than 18% with credit on your cost base.
- GTAs: if you carry platform-ordered goods to unregistered buyers under the entry 21A exemption, expect it to end for those consignments.
The full set of the meeting's decisions is in our 57th GST Council roundup.
Source: CBIC post on X, 10 October 2026; Recommendations of the 57th Meeting of the GST Council, PIB, 8 October 2026 (Release ID 2320934), part C2, item 2; "Frequently Asked Questions (FAQs) on issues related to services", Ministry of Finance, PIB, 9 October 2026, FAQs 12 to 17; Notification No. 17/2025-Central Tax (Rate); list of notifications on taxinformation.cbic.gov.in, checked 13 October 2026.

Comments (0)
No comments yet. Be the first to comment!