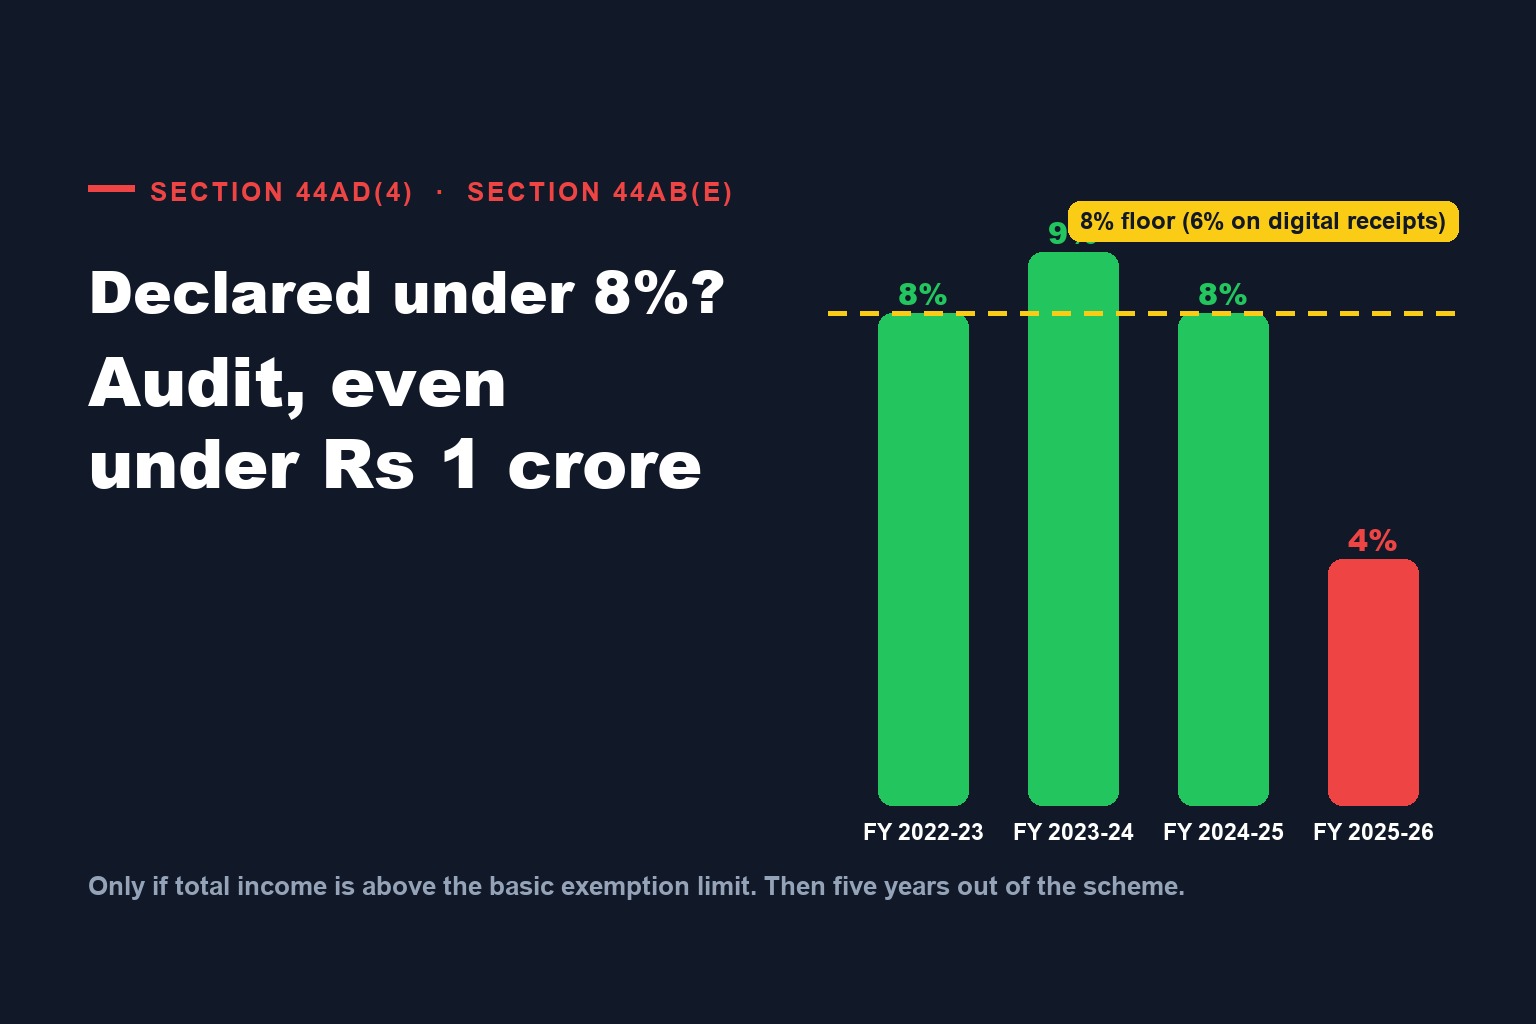
Declared Profit Below 8% or 6%? You May Need a Tax Audit Even Under Rs 1 Crore: The Section 44AD(4) Trap, and Who It Does Not Catch

I write on income tax and GST here, and I write for the business rather than the salaried filer. On the income-tax side that means the presumptive schemes and who is actually eligible for them, the turnover and cash-transaction tests that pull a business into a tax audit, advance tax and the interest that follows when an instalment falls short, capital gains on business assets, and the disallowances that come up in every second scrutiny — cash payments, unpaid statutory dues, TDS not deducted. On GST it means the mechanics a business has to get right the first time: e-invoicing and e-way bill thresholds, reverse charge, ITC reversals on exempt turnover, and place-of-supply questions on interstate and on-site work. I work from the bare Act, the rules and the department's own circulars, and I put the arithmetic in wherever a rule turns on a number, because that is usually where the disagreement is.