
Nothing notified in 2026 changes the annual-filing forms. We went through MCA's full list of notifications and circulars for 2025 and 2026. The forms you will file for FY 2025-26 are the ones MCA substituted by notifications of 30 May and 6 June 2025, all in force from 14 July 2025, when the last 38 company forms moved to the V3 portal. The main changes:
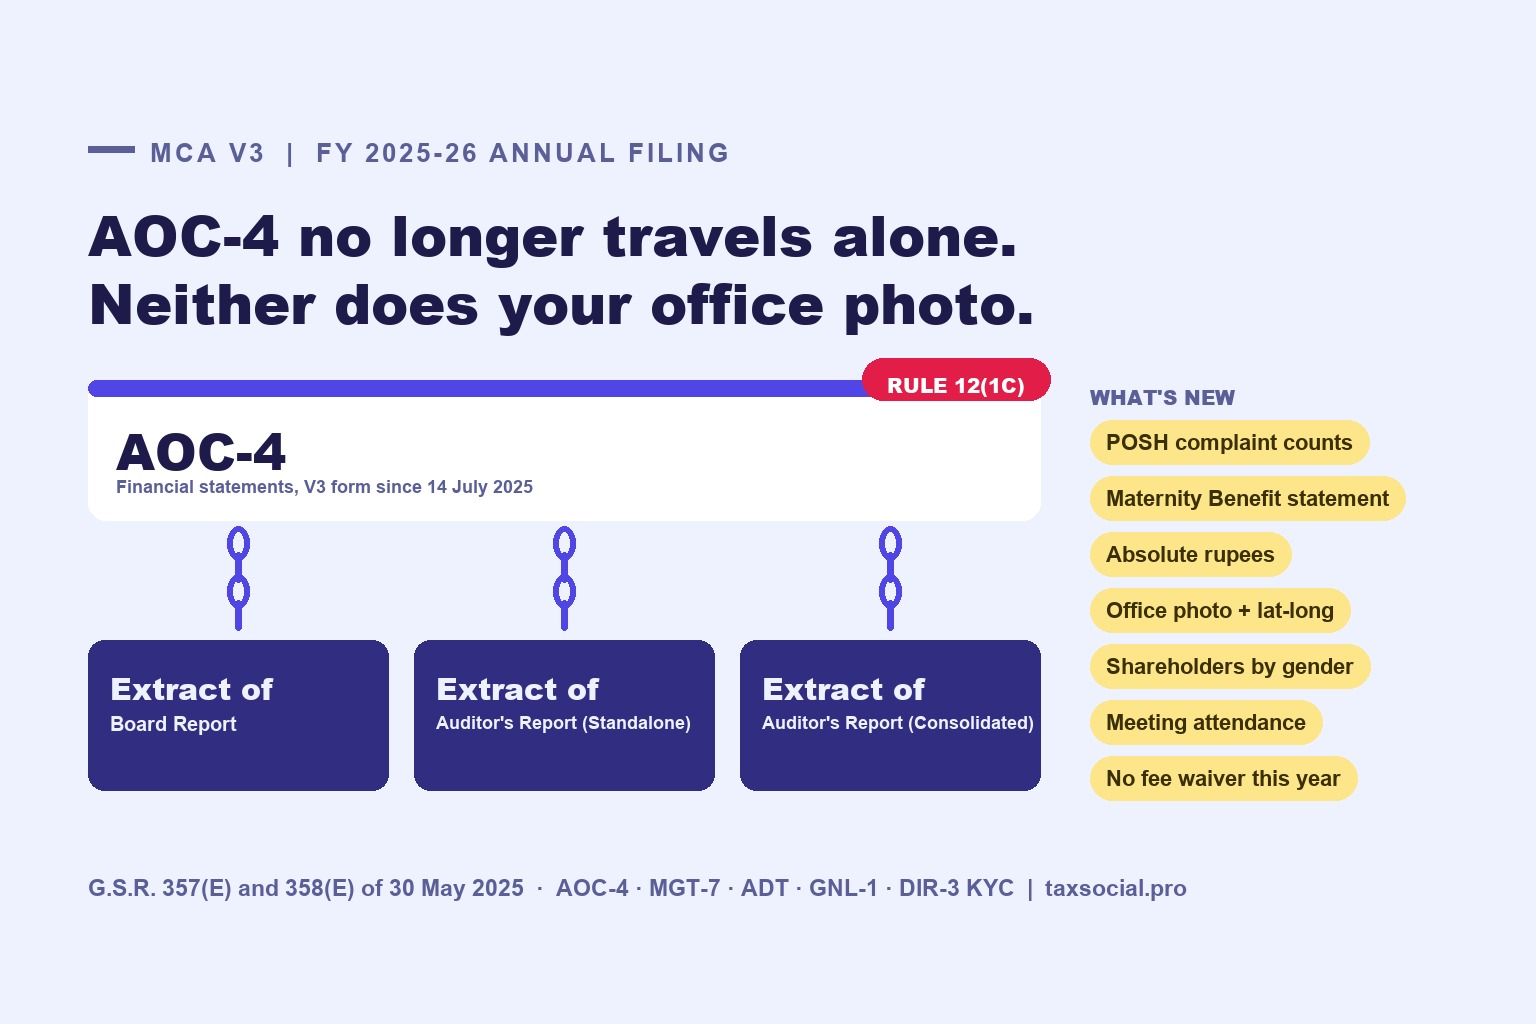
- AOC-4 no longer travels alone. Rule 12(1C) requires e-forms Extract of Board Report and Extract of Auditor's Report to be filed with it.
- The Board's report has two new disclosures: POSH complaint numbers and a Maternity Benefit Act compliance statement.
- MGT-7 and MGT-7A want new data: a photograph of the registered office and its geo-coordinates, shareholder counts by gender, and meeting-by-meeting attendance.
Most companies filed FY 2024-25 on these forms under two fee waivers. This year there is no waiver, and FY 2025-26 is the first financial year that ran almost entirely under the new requirements. Outside the annual forms, DIR-3 KYC is now once every three years, the small company limits have gone up, and the draft Incorporation Rules of April 2026 have not been notified.
1. The timeline, from the Gazette
| Notification | Rules amended | Forms | In force |
|---|---|---|---|
| G.S.R. 357(E), 30.05.2025 | Companies (Accounts) Second Amendment Rules, 2025 | AOC-1, AOC-2, AOC-4, AOC-4 CFS, AOC-4 NBFC (Ind AS), AOC-4 CFS NBFC (Ind AS), CSR-2 substituted; new Extract of Board Report, Extract of Auditor's Report (Standalone) and (Consolidated) | 14.07.2025 |
| G.S.R. 358(E), 30.05.2025 | Companies (Management and Administration) Amendment Rules, 2025 | MGT-7, MGT-7A, MGT-15 substituted | 14.07.2025 |
| G.S.R. 371(E), 06.06.2025 | Companies (Filing of Documents and Forms in XBRL) Amendment Rules, 2025 | AOC-4 XBRL substituted | 14.07.2025 |
| G.S.R. 359(E), 30.05.2025 | Companies (Audit and Auditors) Amendment Rules, 2025 | ADT-1, ADT-2, ADT-3, ADT-4 substituted | 14.07.2025 |
| G.S.R. 361(E), 30.05.2025 | Companies (Cost Records and Audit) Amendment Rules, 2025 | CRA-2, CRA-4 substituted | 14.07.2025 |
| G.S.R. 360(E), 30.05.2025 | Companies (Registration Offices and Fees) Amendment Rules, 2025 | GNL-1 substituted | 14.07.2025 |
| G.S.R. 426(E), 27.06.2025 | Companies (Incorporation) Amendment Rules, 2025 | INC-22A (ACTIVE) substituted | 14.07.2025 |
| G.S.R. 427(E), 27.06.2025 | Companies (Restriction on number of layers) amendment | CRL-1 substituted | 14.07.2025 |
| G.S.R. 452(E), 07.07.2025 | Companies (CSR Policy) Amendment Rules, 2025 | CSR-1 substituted | 14.07.2025 |
| G.S.R. 443(E), 03.07.2025 | LEAP rules amendment | LEAP-1 substituted | On publication |
| G.S.R. 579(E), 26.08.2025 | Regional Director form | RD-1 substituted | 15.09.2025 |
| G.S.R. 603(E), 04.09.2025 | Companies (Compromises, Arrangements and Amalgamations) Amendment Rules, 2025 | CAA-9 to CAA-12 substituted; new CAA-10A | On publication |
| G.S.R. 880(E), 01.12.2025 | Companies (Specification of Definitions Details) Amendment Rules, 2025 | No form; small company limits raised | On publication |
| G.S.R. 943(E), 31.12.2025 | Companies (Appointment and Qualification of Directors) Amendment Rules, 2025 | DIR-3 KYC and DIR-3 KYC Web merged into one DIR-3 KYC Web | 31.03.2026 |
| G.S.R. 300(E), 21.04.2026 | Companies (Registration Offices and Fees) Amendment Rules, 2026 | Fee for DIR-3 KYC Web | On publication |
That is the complete list of form substitutions and new forms in this period. Two other notifications changed form-based compliance without substituting a form: G.S.R. 317(E) of 19 May 2025, on the deadline for separate CSR-2 filing, and G.S.R. 940(E) of 31 December 2025, on the STK-3A indemnity bond for government companies. The list does not include any 2026 notification on AOC-4, MGT-7, PAS-3, SH-7, DPT-3, BEN-2, MSME-1, INC-20A, SPICe+ or DIR-12. None exists. LLP Forms 8 and 11 are also unchanged.
2. The AOC-4 family: one filing is now three
The linked extracts are a rule, not a portal feature
G.S.R. 357(E) inserted rule 12(1C) into the Companies (Accounts) Rules. It requires every company filing AOC-4, AOC-4 CFS, AOC-4 XBRL, AOC-4 NBFC (Ind AS) or AOC-4 CFS NBFC (Ind AS) to file the applicable extract e-forms alongside it, "as the case may be". A standalone filing normally means two extra filings, and the consolidated extract comes in only where consolidated statements are filed:
- Extract of Board Report
- Extract of Auditor's Report (Standalone)
- Extract of Auditor's Report (Consolidated)
For XBRL filers there is a proviso: a signed PDF of the financial statements, authenticated under section 134 and including the Board's report and the auditor's report, has to be attached as well. The XBRL rules were amended to the same effect by G.S.R. 371(E).
In practice this means the Board's report and the audit report are no longer just attachments. Their contents are keyed in as structured data. The Board-report extract asks for every Board and committee meeting with attendance, section 186 loans, guarantees and investments transaction by transaction with the MGT-14 SRN, the CSR computation and projects, and the employee headcount at year end split female, male and transgender. The standalone audit-report extract asks for the opinion, basis for opinion, emphasis of matter, key audit matters, CARO reporting clause by clause, and reporting on internal financial controls. The consolidated extract asks a narrower CARO question: whether the CARO reports of companies in the consolidation carry qualifications or adverse remarks, and if so which company, which clause and why. CSR-2 is also now a linked form to AOC-4 under the same notification. General Circular 02/2025 only gave a transition window, from 14 July to 15 August 2025, for separate CSR-2 filings against an AOC-4 filed on V2.
Two new disclosures in the Board's report itself
The same notification changed what the Board's report must say, not just how it is filed. Under rule 8(5) of the Accounts Rules:
- Clause (x), the statement on the Internal Complaints Committee under the POSH Act, must now give the number of sexual harassment complaints received in the year, the number disposed of, and the number pending for more than ninety days.
- New clause (xiii) requires a statement on compliance with the provisions of the Maternity Benefit Act, 1961.
A Board's report for FY 2025-26 drafted from last year's template is likely to miss one or both. They also feed straight into the Board-report extract, so a gap in the report becomes a blank in the form.
New fields in AOC-4
- All figures in absolute rupees, not rounded. The form's instructions say so in terms. Financial statements presented in lakhs or crores have to be converted.
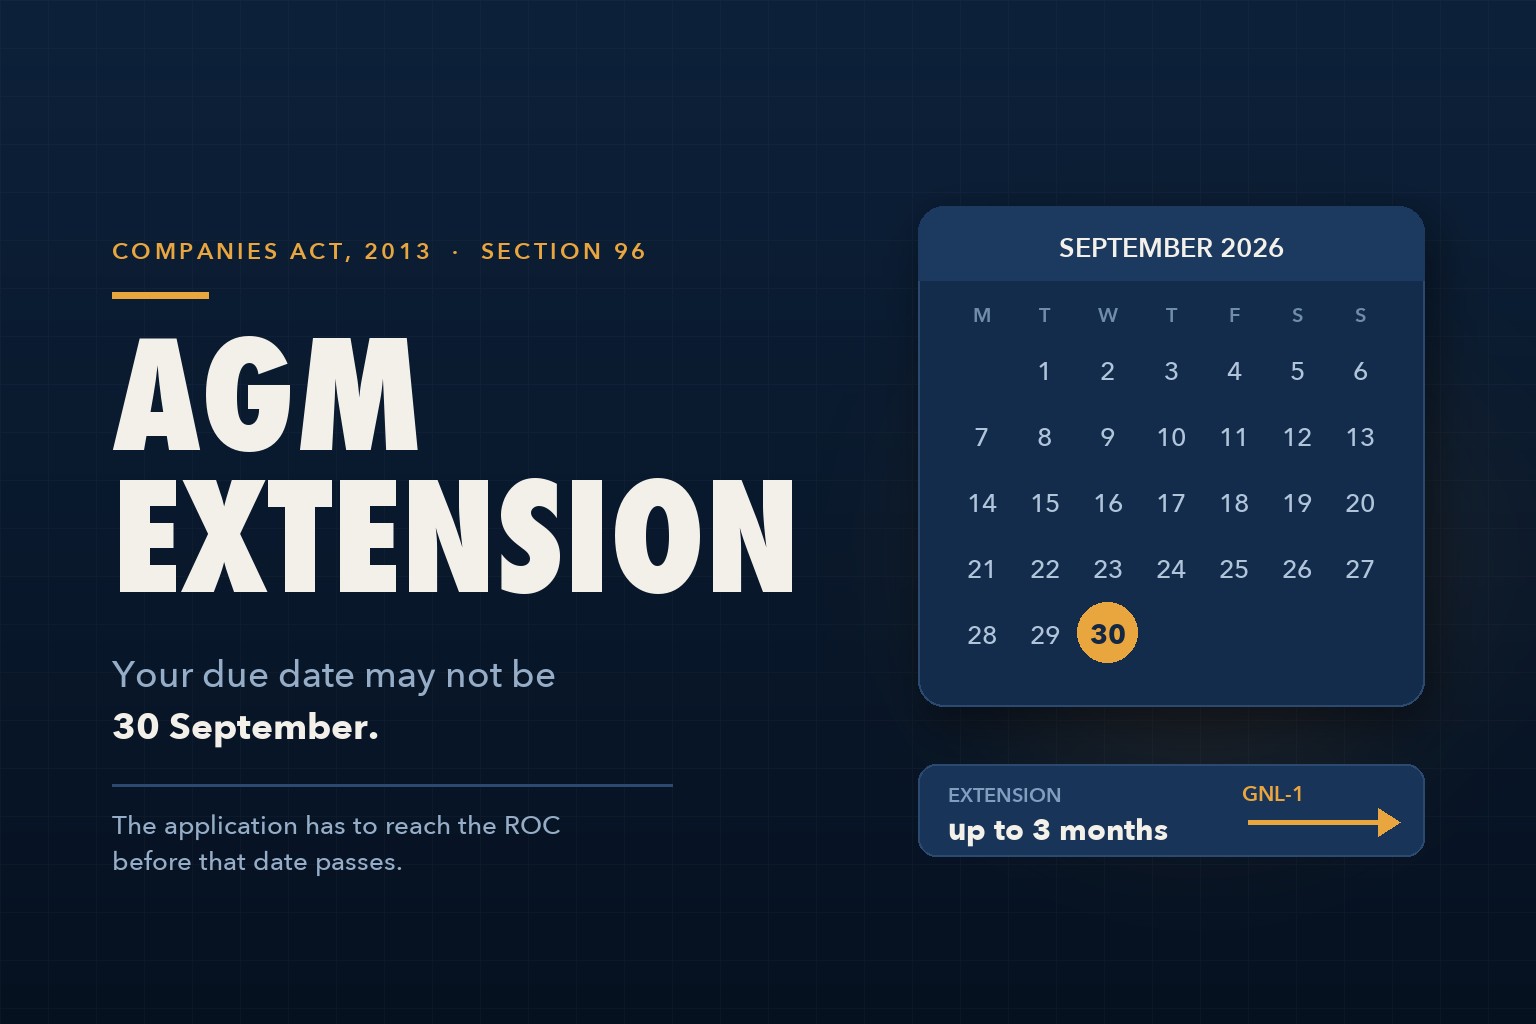
- AGM details: the due date, whether an extension was granted, the GNL-1 SRN and the extended date. An extension order now has to be quoted, not just held on file. See our pieces on the extension and on what to do if the AGM is late.
- The SRN of ADT-1, and details of the member signing for the audit firm.
- Where books are kept electronically, the postal address of the servers holding the accounting data, the service provider, and whether they are kept on cloud.
- A column for the reason for any change in pre-filled previous-year figures.
- A segment on secretarial audit: whether it applies, any qualifications, and the secretarial auditor's details.
3. MGT-7 and MGT-7A: the annual return asks new questions
G.S.R. 358(E) substituted MGT-7, MGT-7A and MGT-15. The new annual return asks for:
- the registered office's latitude and longitude, and a mandatory photograph of the registered office showing the external building with the company's name prominently visible;
- whether the AGM was held, its due date, and any GNL-1 SRN and extended date;
- turnover and net worth;
- shareholding by promoter and public category, and the number of shareholders by gender: female, male, transgender, and non-individual;
- the physical and demat break-up of the paid-up capital;
- every members', Board and committee meeting with attendance, including director-wise attendance;
- remuneration of the MD and whole-time directors, of the CEO, CFO and company secretary, and of other directors;
- penalties, punishments and compounding;
- a declaration under rule 9(4) naming the designated person responsible for beneficial-interest disclosures, with a DIN, PAN or membership number.
MGT-7A, for One Person Companies and small companies, carries the same photograph, geo-coordinates, turnover and net worth, and gender fields in a shorter form. MGT-15, the report on the AGM that every listed public company files under section 121, is restructured around the day, start and end time, venue, quorum, business transacted, any adjournment, and a fair summary of the proceedings.
The photograph catches people out. It must show the building and the company's name. A company operating from a shared or virtual office without its name displayed has a problem that has to be fixed at the office, not in the form.
4. What to collect now, before drafting
Most of the difficulty with these forms is data nobody collected during the year. For FY 2025-26, get these in hand before you start:
- A current photograph of the registered office with the name visible, and its latitude and longitude.
- The attendance record for every Board, committee and general meeting in the year, director by director.
- The POSH register: complaints received, disposed of, and pending beyond ninety days.
- A basis for the Maternity Benefit Act statement.
- Headcount by gender at 31 March 2026, and shareholders by gender.
- The section 186 register, transaction by transaction, with MGT-14 SRNs where a resolution was filed.
- The ADT-1 SRN, the AGM date, and any GNL-1 SRN and extension order.
- The server address and service provider for the accounting data, and whether it is on cloud.
- The name and ID of the designated person under rule 9(4).
- The financial statements converted to absolute rupees, and the audit report's KAMs and CARO answers in a form that can be keyed in.
5. The fee position: no waiver this year
When the new forms went live in July 2025, MCA took the old ones offline from 18 June to 13 July 2025 (General Circular 01/2025). Where a due date fell between 18 June and 31 July 2025, it allowed filing without additional fee up to 15 August 2025. For FY 2024-25, General Circulars 06/2025 (17 October 2025) and 08/2025 (30 December 2025) allowed the annual forms to be filed without additional fee, first to 31 December 2025 and then to 31 January 2026. Both circulars were for FY 2024-25 only, and both said they did not extend the time for holding an AGM.
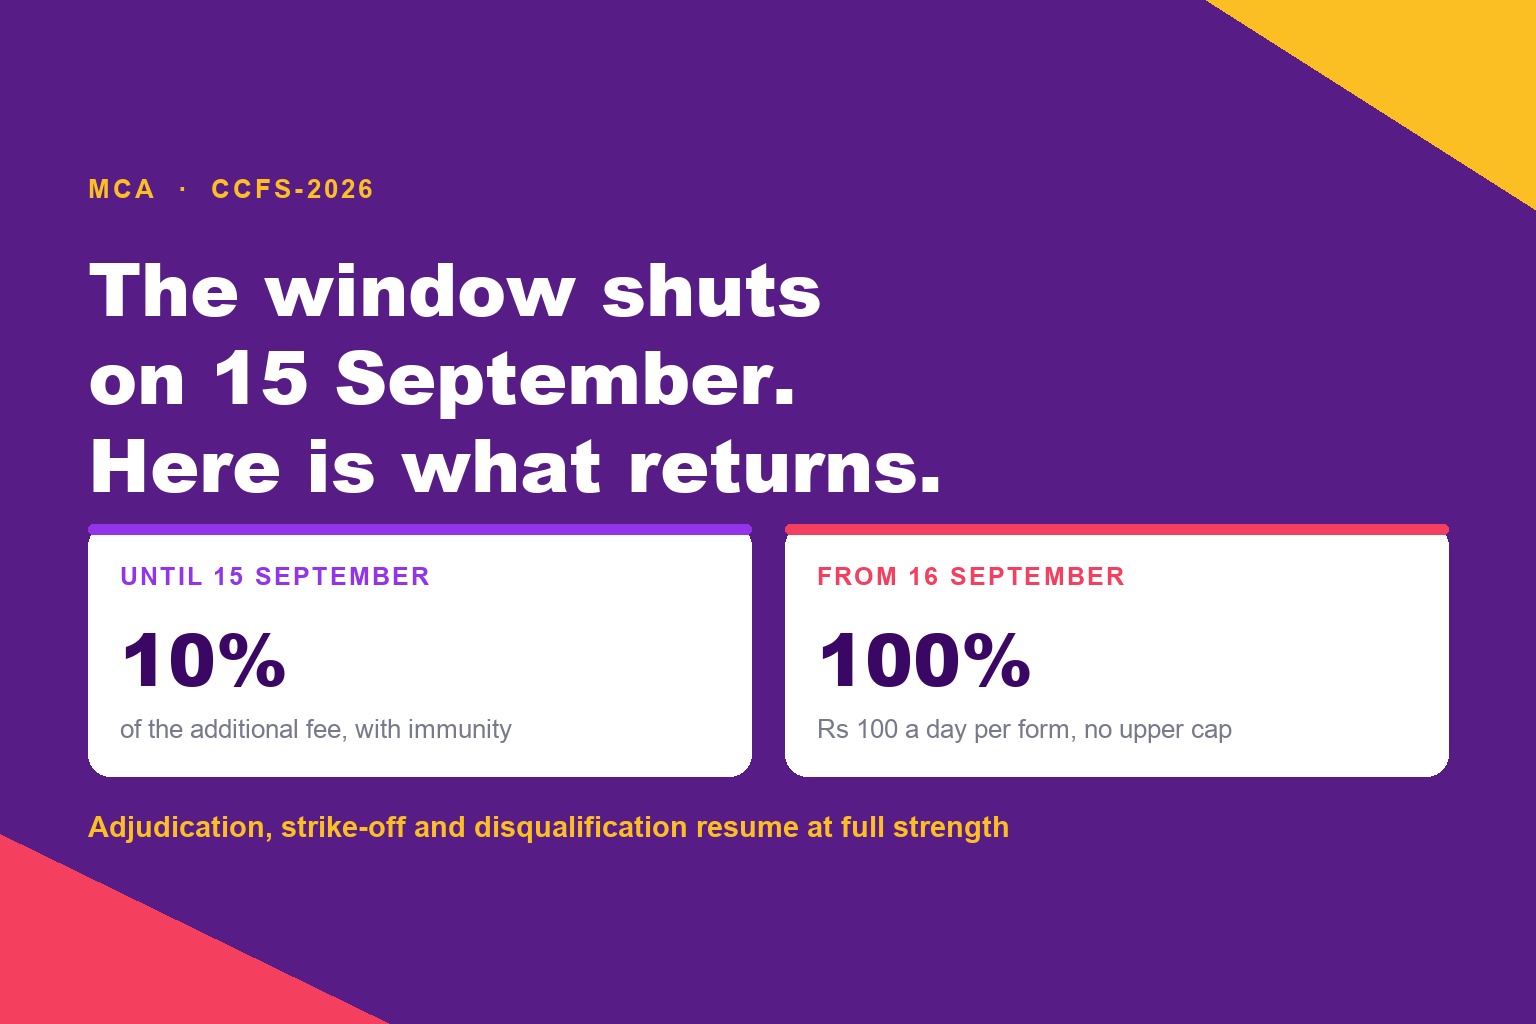
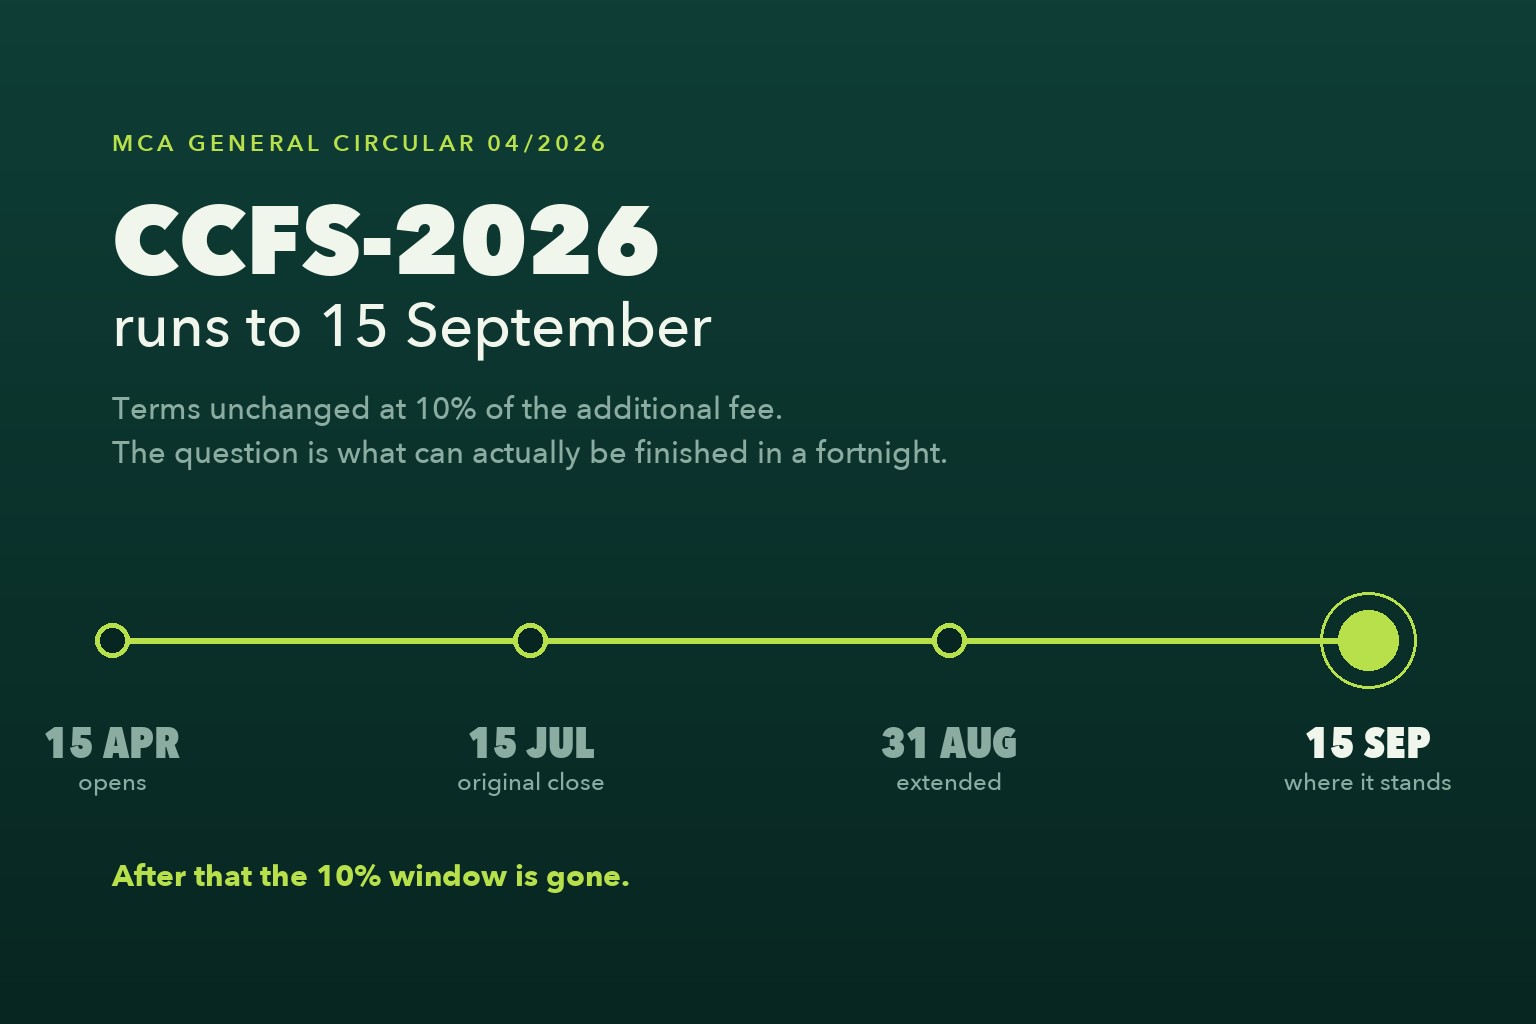
There is no equivalent circular for FY 2025-26. The CCFS-2026 amnesty, which let old defaults be cleared at a tenth of the additional fee, closed on 15 September 2026. So AOC-4 is due within thirty days of the AGM and MGT-7 within sixty. The ordinary additional fee applies from the day after, and nothing suggests MCA will absorb the cost of a second learning year.
6. The other forms that changed
- ADT-1 to ADT-4 (G.S.R. 359(E)): all four substituted. ADT-4, the auditor's report of fraud to the Central Government, must now be filed electronically.
- CRA-2 and CRA-4 (G.S.R. 361(E)): cost auditor appointment and cost audit report, substituted.
- GNL-1 (G.S.R. 360(E)): substituted, now with the purposes listed, including extension of the AGM by up to three months and compounding, with a detailed compounding block. The fee table itself was not changed.
- INC-22A (ACTIVE) (G.S.R. 426(E)): now asks for the office's geo-coordinates, photographs of the external building and of the office inside, the inside one showing at least one director or KMP who signed the form, OTP-verified e-mail, and details of auditors, cost auditors and KMP.
- CSR-1 (G.S.R. 452(E)), CRL-1 (G.S.R. 427(E)) and LEAP-1 (G.S.R. 443(E)): substituted.
- Fast-track mergers (G.S.R. 603(E), 4 September 2025): section 233 was opened to more classes, each with conditions. They include unlisted companies whose outstanding loans, debentures and deposits are within ₹200 crore with no default, a test that applies to every company involved, both within thirty days before the section 233(1) notice and on the date the scheme is filed. They also include holding and subsidiary companies (not where the transferor is listed), fellow subsidiaries (transferors must not be listed), and a foreign holding company merging into its Indian wholly owned subsidiary. CAA-9 to CAA-12 were substituted and a new CAA-10A (auditor's certificate) added. RD-1 was substituted from 15 September 2025.
- DIR-3 KYC (G.S.R. 943(E), in force 31 March 2026): the two KYC forms are merged into a single DIR-3 KYC Web. KYC is now due by 30 June following every third consecutive financial year, instead of every year, and any change in mobile, e-mail or address is filed within thirty days. The fee is nil on time, ₹5,000 late or on reactivation, and ₹500 per change filing (G.S.R. 300(E)). Our DIR-3 KYC fee article has the detail.
Small company limits, and the MGT-7A question
G.S.R. 880(E), in force from 1 December 2025, raised the prescribed limits for a small company to paid-up capital not exceeding ₹10 crore and turnover not exceeding ₹100 crore. A private company within both limits (and not a holding or subsidiary company, a section 8 company, or one governed by a special Act) files the shorter MGT-7A, among the other small-company concessions. A company that filed MGT-7 last year may qualify for MGT-7A this year. Section 2(85) tests paid-up capital and the turnover in the profit and loss account for the immediately preceding financial year. Run both tests on the company's own figures before choosing the form.
7. What has not changed, and what is only proposed
- The draft Companies (Incorporation) Amendment Rules, 2026, put out for comment on 8 April 2026, would merge several incorporation-stage forms and omit DIR-12 for first directors. As of 27 September 2026 they have not been notified. SPICe+, INC-20A and DIR-12 are filed as before. Our April article describes the draft.
- PAS-3, SH-7, PAS-6, DPT-3, BEN-2, MSME-1: no form amendment in 2025 or 2026.
- LLP Forms 8 and 11: no LLP Rules amendment in the period.
- Which ROC you file with may have changed. New ROC and Regional Director jurisdictions were notified in October 2025 (S.O. 4849(E) to 4852(E)) and, per MCA's portal notice, took effect on 16 February 2026. The forms are the same; the office they go to may not be.
Quick answers
We filed FY 2024-25 on the old AOC-4 before 14 July 2025. Is anything different for us?
Everything in sections 2 and 3. This will be your first filing on the new forms, and the first to need the Board-report and auditor's-report extracts.
Is the Extract of Board Report optional for small or private companies?
No exemption appears in rule 12(1C). It applies to every company filing any AOC-4 variant, "as the case may be". The consolidated auditor's-report extract applies only where consolidated statements are filed.
Can the office photograph be of a shared workspace?
The form asks for the external building with the company's name prominently visible. If the name isn't displayed there, the fix is to display it.
Has MCA extended the due dates for AOC-4 or MGT-7 for FY 2025-26?
No. There is no circular for FY 2025-26 as of 27 September 2026. The dates run from the AGM, or from the date it should have been held.
Sources
- Gazette of India, Extraordinary, Part II, Section 3(i): G.S.R. 357(E), 358(E), 359(E), 360(E) and 361(E) of 30.05.2025; G.S.R. 371(E) of 06.06.2025; G.S.R. 426(E) and 427(E) of 27.06.2025; G.S.R. 443(E) of 03.07.2025; G.S.R. 452(E) of 07.07.2025; G.S.R. 579(E) of 26.08.2025; G.S.R. 603(E) of 04.09.2025; G.S.R. 880(E) of 01.12.2025; G.S.R. 943(E) of 31.12.2025; G.S.R. 300(E) of 21.04.2026.
- MCA General Circulars 01/2025 and 02/2025 (16.06.2025), 06/2025 (17.10.2025), 08/2025 (30.12.2025), and 01/2026 to 04/2026.
- MCA portal notice listing the final 38 company forms launched on V3 on 14 July 2025.
- Companies Act, 2013, section 2(85); Companies (Accounts) Rules, 2014, rules 8(5) and 12(1C); Companies (Management and Administration) Rules, 2014, rules 9(4) and 11.
This article reflects notifications and circulars on MCA's site as at 27 September 2026. MCA revises forms by notification and sometimes changes the portal version without one, so check the form version on V3 when you file. Nothing here is advice on your company's facts.
Comments (0)
No comments yet. Be the first to comment!